

Banks in Car Leasing
The creation of dynamic and unparalleled growth in the individual leasing segment.
There are many similarities between the consumer's reaction to the energy crisis and leasing companies' fears about banks entering into the car leasing field. There are a great many people in this country who feel that the press has overly alarmed consumers and that the national administration has not acted properly in alleviating falsehoods about our energy resources. In contrast, it appears to me that many individuals in the leasing industry have become overly alarmed and look at banks with the assumption that banks have all the money necessary, as well as the desire to take over the car leasing industry. I categorically refute the position of any banker or independent lessor who takes such a stance. I base this postulation on some of my bank's experiences and what I feel will probably occur.
Maryland National has been in the car leasing business for nearly three years and has witnessed some of the rewards and some of the inherent pitfalls apparent in this very specialized field. It is my firm belief that the net effect of banks entering the car leasing field will be the creation of dynamic and unparalleled growth in the individual leasing segment. This expansion can profit existing leasing companies as much as, or more, than the banks which promote leasing as a new service.
Our entre' into car leasing was based on two premises - first, the trend toward individual leasing was growing each year and we were concerned with the possibility of erosion in our car loan portfolio, especially if leasing continued to become more popular in years to come. Secondly, our bank's decision paralleled one which certainly each one of your respective firms made. We saw car leasing as being profitable and were aware of the gross return involved. Many bankers will view car leasing as a natural extension of their car lending activities and may tend to be somewhat myopic at first, only to discover the many dissimilarities between car financing and car leasing. We had to learn these idiosyncrasies. We had deliberated over our leasing venture and determined that we would test the water, if you will, before diving headlong into a massive commitment to this service. Our activity in automobile leasing is set up as a function of a national bank, although we do have an equipment leasing company operating in our holding company. Our car leases are all open-end leases.
Early in our new endeavor we found that leasing cars was a different "ball game" than financing them. I'll relate a few of our experiences only because I believe other banks will profit by our mistakes and the fears of some of you may be allayed.
It has been said that some bankers are not good salesmen. In the typical car loan transaction the role of the lender is that of an "order taker." The customer has already, in many cases, arranged to purchase the car before applying for a loan, or at least knows what model he is going to buy. We discovered to our dismay this was generally not the case when a customer wanted to lease a car. After three years, it is evident to us that car leasing involves more than just order taking. Quoting accurate monthly rentals, closing the sale of the lease with the customer, getting the lease signed, securing proper insurance coverage and purchasing the car as well as close follow-up, all represented many new elements for our leasing representatives who were primarily installment loan oriented.
During the first year in operation, small problems cropped up but it finally started to gel and then came the early, terminations and disposals. We made mistakes, but corrected them because we recognized that leasing cars was a sophisticated service with a high degree of financial risk. There are other traps for new lessors whether they're banks or leasing companies.
[PAGEBREAK]
(1)-What form of advertising will best accomplish the promotion of this service? How many advertising dollars will be required to develop the projected number of leases? Will the income projections of the leasing operation support the expense for promotion of the new service? Or will the bankers' rationale be "Advertising for car leasing provides great institutional benefits."
(2)-Will the banker truly recognize all the expenses involved in car leasing when determining the return on investment, or will some "creative accounting" be employed? The manpower commitment, i.e., numbers of employees to numbers of leases outstanding is far greater than a similar comparison to loans outstanding. The fact is that car leasing, while being more profitable, is also far more expensive than car financing.
(3)-How about the credit judgment of the car leasing manager who is constantly under pressure to lease more cars?
We have had to be careful not to let the number of units taint some of our fundamental credit judgment. We've not had many repossessions, but I see the strain of lease volume versus sound judgment as being a problem for anyone who chooses to enter the leasing arena. I also wonder if the individual lessee places the same emphasis on prompt payment when leasing as he does when he's borrowing.
Now, what about the impact of banks entering the leasing field? First of all, the yield doesn't currently exist in fleet leasing to cause large numbers of bankers to get into that competitive market. This is not to say that one or two more might not try, but not the masses. That leaves the individual segment, and it is well known that individual leasing is becoming more popular each year with hardly any stimulation from manufacturers or independent lessors. Compare for a moment the entry of banks into car leasing with their entrance into the credit card field in the mid-sixties. Think about what's happened in the credit card industry in the last decade. I think it is fair to say that the credit card is now an American way of life.
Many banks have entered the leasing field and many are standing in the wings waiting for the "smoke to clear." Banks must, however, recognize that there are pitfalls in leasing and work with groups such as AALA, to perfect the science and promote the concept.
Individual car leasing will, in my opinion, experience dramatic growth in the years which are ahead of us in spite of the energy crisis and the volatilidity of the economy. I attribute this to the ingenuity of independent lessors, combined with the creativity of banks which choose to act as lessors. I am convinced that banks in leasing will be healthy for the industry. I've watched one horse leasing operations come and go and as they did, some left scars on the car leasing industry. I am thoroughly convinced that independent lessors are highly skilled automotive people who are equipped to meet new challenge whether it comes from banks, manufacturers, large finance companies, insurance companies or even an energy crisis!
This article was adopted from a recent speech presented by Mr. Ray Nichols, Vice President, Maryland State Bank.
More Operations
Reading the Global Signals: What AI and the Energy Transition Mean for Fleets Now
How can fleet managers navigate a never-ending, changing industry landscape?
Read More →
90% Use Telematics. Are Fleets Getting Safer? | AF News Recap
This week, we're breaking down which industries have the highest rates, how Jamie McKay manages 2,400 vehicles, what's happening with the 2027 fleet awards, and why software-defined vehicles could introduce new costs.
Read More →
What's Best Handled by an FMC, and What's Better Done Directly?
Fleet managers continue to rely on FMCs for essential services but are taking a closer look at where working directly with suppliers can improve efficiency and responsiveness.
Read More →
Fleet Meets: Erin Gilchrist
Meet Erin Gilchrist, the inaugural Mike Antich Spirit of Fleet Award winner, as she shares insights on leadership, mentorship, the power of industry connections, and why people remain at the heart of fleet's future.
Read More →
How 2026 Fleet Visionary Jamie McKay Manages 2,400 Vehicles Across 37 States
How do you keep 2,400 vehicles running across 37 states? Fleet Visionary Award winner Jamie McKay shares how collaboration, flexibility, and a few simple strategies help her tackle fleet management challenges at Aptive Pest Control.
Read More →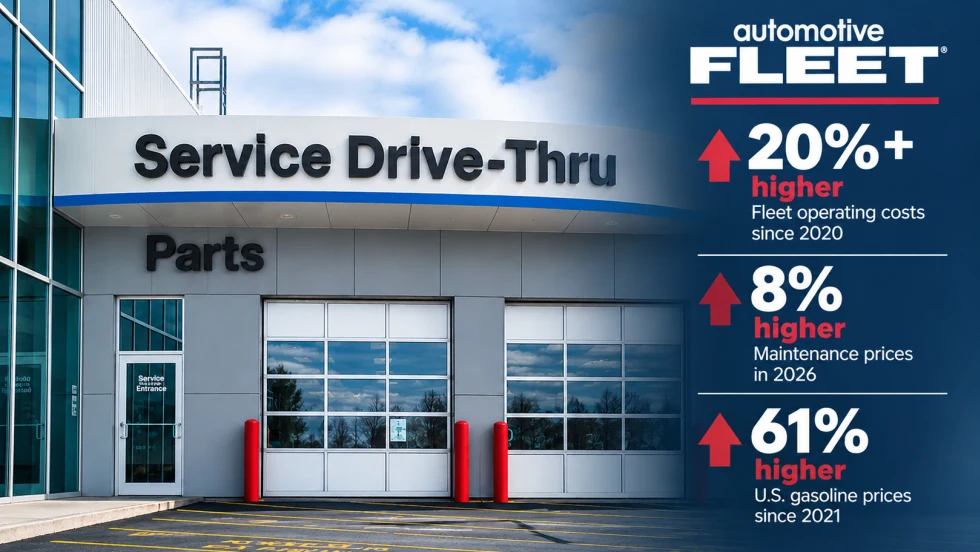
Managing Fleet Costs in an Era of Permanent Volatility
Fleet operating costs have risen more than 20% since 2020, raising a key question: When does extending a vehicle's service life stop making financial sense?
Read More →
The Next Evolution of Fleet Management: Autonomous Operations
This opening keynote session at the Fleet Forward Conference highlights the future of autonomous driving for fleets.
Read More →
How to Reduce the Total Cost of Risk From Catalytic Converter Theft
A stolen catalytic converter can cost fleets far more in downtime and lost productivity than in repairs. A total-cost-of-risk approach can help fleet managers quantify their exposure and prioritize theft prevention.
Read More →
Personal-Use Charges Rise as Vehicle Values Fall | AF News Recap
Personal-use charges are climbing, wholesale used-vehicle values are declining, and commercial fleet sales growth is slowing. This week, we're breaking down the latest fleet data, plus how Element Fleet Management is helping Waymo prepare for its first Canadian robotaxi market.
Read More →
Here's When You Should Make an Exception to Fleet Policy
Fleet policies are designed to create consistency, but not every driver or situation fits neatly within standard rules.
Read More →