Reimbursement is Unfair to Employees
If employees are your greatest asset, why treat them unfairly with a driver reimbursement program? I have yet to hear of a company that reimburses at a rate that fully compensates drivers for the actual cost of operating a vehicle, especially in this era of escalating fuel prices.

If employees are your greatest asset, why treat them unfairly with a driver reimbursement program? I have yet to hear of a company that reimburses at a rate that fully compensates drivers for the actual cost of operating a vehicle, especially in this era of escalating fuel prices. In addition, the cost of gas, insurance, license/registration fees, and vehicle maintenance vary substantially by region. If the reimbursement doesn’t cover actual expenses, a driver, in essence, ends up with a pay reduction. He or she must make up the difference between the reimbursement amount and the actual cost of operating the vehicle. What’s fair about this?
In the final analysis, it is more expensive for employees to use their personal vehicles for business than for a business to offer company vehicles. As a volume buyer, a company acquires vehicles at a wholesale cost, while employees pay retail. Secondly, a company can finance a vehicle at a lower cost than an employee. A company also has lower maintenance costs by participating in a national account program, while an employee pays retail.
Many employees lease their personal vehicles. However, it is difficult to afford a retail lease when the average fleet driver drives 24,000 miles per year. Most retail leases are structured for drivers who drive 12,000-15,000 miles per year. High-mileage drivers are usually upside down at end-of-lease with a balloon payment for excess mileage. Even if a driver purchases a vehicle, after two or three years, the resale value is so low because of high mileage, they are forced to keep driving the vehicle or take a significant loss selling it or trading it in.
Some employees can’t afford a new vehicle. Often, salespeople are recruited straight out of college. At this age, employees have little or no credit history. They often have no cash for down payments. Many fleet managers, who also manage a reimbursement program, report that younger employees often need the company to co-sign a loan or lease for their personal vehicle. Sometimes employees run short of cash and have to ask the company for a loan to repair their personal vehicle to continue working.
Negative Effect on Morale
Reimbursement negatively affects employee morale since some drivers feel they are underpaid. If an allowance is provided to a low-mileage driver, the employee enjoys additional compensation. For high-mileage drivers, a car allowance may not be sufficient to cover the employee’s cost, which demoralizes the employee because he or she feels they are subsidizing the company.
Different vehicle requirements, geography, and regional cost of living require a flexible reimbursement policy to cover these diversities or inequities will exist. Because of built-in inequities in a reimbursement program, some drivers may feel they are being forced to subsidize the company’s operating costs. As a consequence, reimbursement opens the door for padding business miles to increase allowances. Also, some employees may attempt to get reimbursed for unauthorized expenses. Who monitors this?
Another concern is reimbursement can be considered taxable income by the federal government and some states, if not handled correctly. As such, car allowances are taxable to the employee and the company is subject to its portion of the FICA tax. On average, the employee’s combined state and federal tax burden increases, which amounts to a direct reduction in salary. In addition, reimbursed employees may be subject to a possible IRS audit since mileage and vehicle expense deductions are auditable.
Even though they receive a car allowance, many employees also expect a supplemental reimbursement for fuel. If a company does reimburse for fuel, it cannot determine if fuel is purchased for personal use or business use. In addition, employees will constantly agitate for higher reimbursement as fuel prices and cost of living expense increase (and rightly so).
Typically, employees view a car allowance or reimbursement as additional personal income. Will the reimbursement provided by a company be used for a vehicle (as intended) or will the monies be used to repay a college loan or make a mortgage payment? Insurance is another unfair aspect of driver reimbursement. If driving a personal vehicle, an employee must buy “business insurance,” which costs twice as much as personal auto insurance. The reason for this is if the employee is involved in an accident and does not have business insurance, the personal insurance carrier can deny the claim and incurred loss because it was not advised the personal vehicle is used for business. In addition, a reimbursed driver may not carry adequate personal liability insurance, which puts the company at increased risk. If personal vehicles are used, a minimum amount of liability coverage should be required. However, someone internally must track this, as well as ensure insurance policies are renewed each year.
A Fair Deal
A company-provided vehicle helps create high employee morale. Drivers don't have to worry about securing insurance or paying for unexpected major repairs and routine maintenance. Employees perceive the company values them more if it entrusts them with a company car. It’s a fair deal.
Let me know what you think.
More Operations
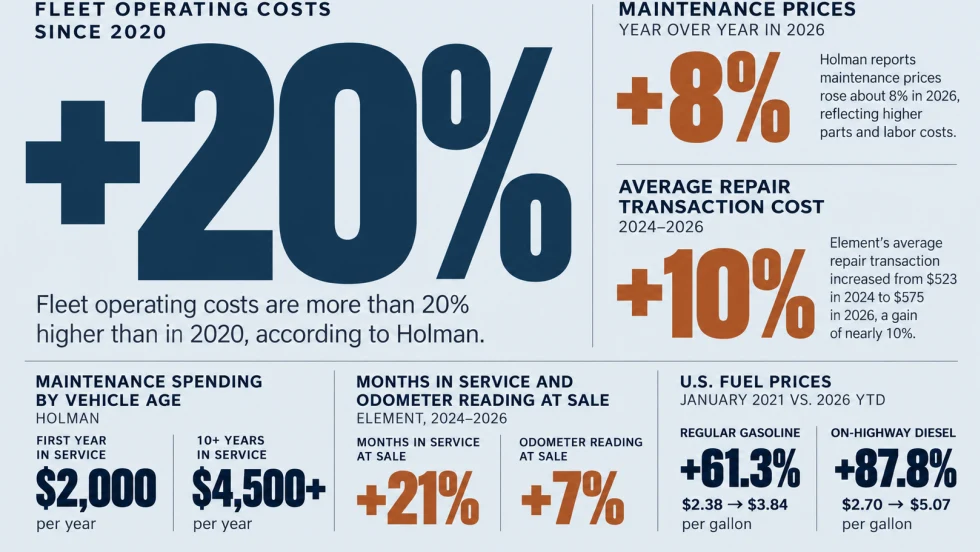
Managing Fleet Costs in an Era of Permanent Volatility
Fleet operating costs have risen more than 20% since 2020, raising a key question: When does extending a vehicle's service life stop making financial sense?
Read More →
The Next Evolution of Fleet Management: Autonomous Operations
This opening keynote session at the Fleet Forward Conference highlights the future of autonomous driving for fleets.
Read More →
How to Reduce the Total Cost of Risk From Catalytic Converter Theft
A stolen catalytic converter can cost fleets far more in downtime and lost productivity than in repairs. A total-cost-of-risk approach can help fleet managers quantify their exposure and prioritize theft prevention.
Read More →
Personal-Use Charges Rise as Vehicle Values Fall | AF News Recap
Personal-use charges are climbing, wholesale used-vehicle values are declining, and commercial fleet sales growth is slowing. This week, we're breaking down the latest fleet data, plus how Element Fleet Management is helping Waymo prepare for its first Canadian robotaxi market.
Read More →
Here's When You Should Make an Exception to Fleet Policy
Fleet policies are designed to create consistency, but not every driver or situation fits neatly within standard rules.
Read More →
AI-Native or AI-Acquired: What Should Fleet Managers Look for in an AI Platform?
Six questions can help fleet managers look beyond AI marketing claims to evaluate integration, data access, and real-world operational performance.
Read More →
A buyer's guide to fleet management software in 2027
Buying fleet management software in 2027 means looking beyond features and price. As fleet operations, technology and expectations evolve, this guide explores what today’s fleet professionals should consider when choosing a system that can deliver value now and adapt to what comes next.
Read More →
What Will Shape the Next Era of Fleet Management?
EVs, AI, and autonomous vehicles are reshaping fleet management. Discover what’s ahead—and how fleet leaders can prepare for the next era.
Read More →
How Fleets Can Recruit and Train Veterans for Technician Roles
Here's how the technician shortage has affected uptime for fleets, and what to do about it.
Read More →
Avis Budget Group Deploys Neology Toll Management Technology Across Major Brands
Neology’s neoFleet platform will manage toll transactions and toll-authority operations for vehicles across Avis, Budget, Payless, Budget Truck and Zipcar.
Read More →