


Keep Reading: The R Words Powering Business Revenue
Understanding Insurance Coverage for Leased, Personal-Use, and Company Fleet Vehicles
Employees driving leased or rented vehicles bring up some viable insurance concerns.
July 10, 2025
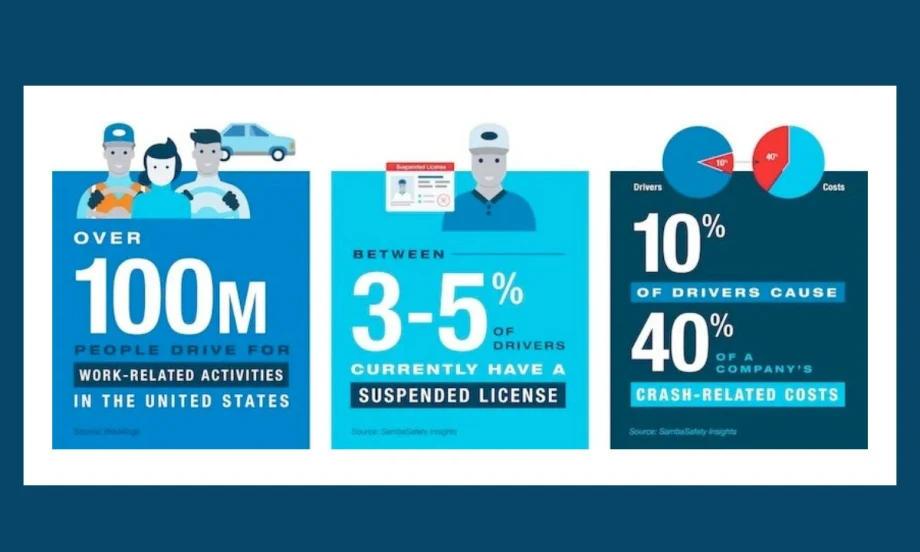
MVR checks and safety agreements help mitigate liability in times of insurance uncertainty.
Photo: Samba Safety / Judie Nuskey
5 min to read
In today’s workplace, company driving responsibilities extend beyond traditional fleet vehicles. Employees may drive leased vehicles, rent cars for business travel, or use their own cars for work errands. With this diversity comes a critical question: what insurance coverage is required, and who is liable when crashes happen?
Personal Vehicle Use for Work
When employees use their personal vehicles for business purposes, their personal auto insurance is the first line of defense. However, most personal policies do not provide coverage for business use unless specifically endorsed. That’s why employers must ensure drivers meet minimum insurance thresholds. It is equally important that companies require insurance thresholds and stipulations should a policy be cancelled.
For example, under a Personal Vehicle Reimbursement Program (PVRP) like the one used for a HUB International client, drivers must carry:
Bodily Injury Liability: $500,000 combined single limit (CSL) or $500,000/$500,000 split limits
Property Damage Liability: $50,000 minimum
Uninsured Motorist: $100,000/$300,000
Medical Payments: $2,000
Deductibles: $500 for both collision and comprehensive Employees must also be listed on the policy as a named or additional insured and ensure the declaration address matches their HR record.
Company-Owned and Leased Fleet Vehicles
When vehicles are company-owned or leased through a fleet management provider, coverage requirements and oversight are typically more formalized. During a recent conversation, Amanda Mainville, Director of Client Relations at Motorlease, explained, “There’s a misconception that leasing companies automatically assume liability. But unless specified in the lease, the responsibility of insuring the vehicle, including liability, comprehensive, and collision, falls on the company leasing the vehicle.”
Amanda also highlighted that if a company vehicle is permitted for personal use that the company needs to be certain that they are outlining this in a car policy. She recommended employers create clear personal use agreements and confirm insurance declarations match intended vehicle usage.
Fleet insurers like GMI require:
No major violations (e.g., DUI, reckless driving) within the last 3 years
A valid U.S. driver’s license for a minimum of 2 years
No more than four combined accidents or violations within a three-year period
Rental Vehicles for Business Use
When employees rent vehicles for work, coverage depends on both company policy and rental terms. Amanda noted that many companies fail to centralize rental bookings, leading to uncertainty about coverage.
“It’s essential to align with a corporate rental account. This gives you contractual control over insurance coverage and often includes liability protection.”
She recommends issuing employees a rental car insurance FAQ outlining:
Whether to accept or decline the rental company's coverage
Whether corporate credit cards offer secondary insurance
What steps to take in case of an accident
A Hired and Non-Owned Auto (HNOA) policy is a must-have, as it protects the company when employees drive rentals or their own cars for work.
What is FAVR and How Does It Affect Insurance?
The Fixed and Variable Rate (FAVR) program is an IRS-sanctioned reimbursement model that allows employers to compensate employees tax-free for using their personal vehicles for business purposes. It replaces traditional company car programs or taxable car allowances and offers reimbursement that reflects both:
Fixed costs: Depreciation, insurance premiums, registration
Variable costs: Fuel, maintenance, and wear-and-tear based on mileage and location
With FAVR, employees must maintain appropriate insurance, typically with higher liability limits than standard personal use policies. Employers should define insurance requirements and verify proof of coverage to protect both the driver and the business. It is recommended that the insurance policy should state that the vehicle is driven for business use.
By shifting away from fleet ownership, companies reduce capital costs while still maintaining control and compliance. FAVR also encourages responsible driving and reduces employer liability, as long as personal vehicle use is properly managed and documented.
Liability and Risk Management Considerations
No matter who owns the vehicle, if it’s being used for work, the employer could be held liable. Organizations should:
Conduct Motor Vehicle Record (MVR) checks at hire and annually
Set and enforce clear driver eligibility standards
Provide driver safety training and coaching
Use continuous MVR monitoring for high-risk drivers
Review Motor Vehicle Records (MVRs) at hire and annually thereafter, as recommended by industry experts and supported by internal fleet safety programs. Organizations should use a customized scoring system to track driving behavior over time and identify high-risk drivers.
Sample MVR Evaluation Framework (Adapted)
A modernized MVR evaluation system might assign points based on the severity of violations, such as:
12 Points (High Risk)
Driving under the influence (DUI/DWI)
Reckless driving, racing, or hit-and-run
Speeding more than 20 mph over the limit
Using a handheld phone or texting while operating a commercial vehicle
Not wearing a seat belt in a commercial vehicle
6 Points (Moderate Risk)
Speeding 15–20 mph over the limit
Passing a stopped school bus
Any preventable accident
Driving on a suspended license
Seat belt violations in a personal vehicle
DUI involving off-road or recreational vehicles
Distracted driving or mobile device use in a personal vehicle
3 Points (Low Risk)
Minor moving violations: following too closely, improper lane change, ignoring traffic signals, or speeding less than 15 mph over the limit
Drivers who accumulate 12 points or more within a 3-year period may be considered high risk and subject to additional safety interventions, training, or loss of driving privileges.
Amanda Mainville reinforced that “Insurance is only part of the story—you also need a process for qualifying drivers. Documentation and accountability are key in the event of a claim.”
Next Steps for Safer Fleets
Whether an employee is driving a personal vehicle under FAVR, a leased company car, or a rental, liability and insurance coverage must be clearly defined. Employers can mitigate risk by implementing comprehensive policies, verifying insurance compliance, and leveraging programs like FAVR to increase efficiency, reduce costs, and ensure legal compliance.
More Vehicle Research
Your Fleet Experience Deserves a Vote in the 2027 Fleet Awards
Cars, trucks, vans, SUVs, and upfits. Help choose the 2027 fleet award winners and unlock early-access resources for voters. Ballots close December 31.
Read More →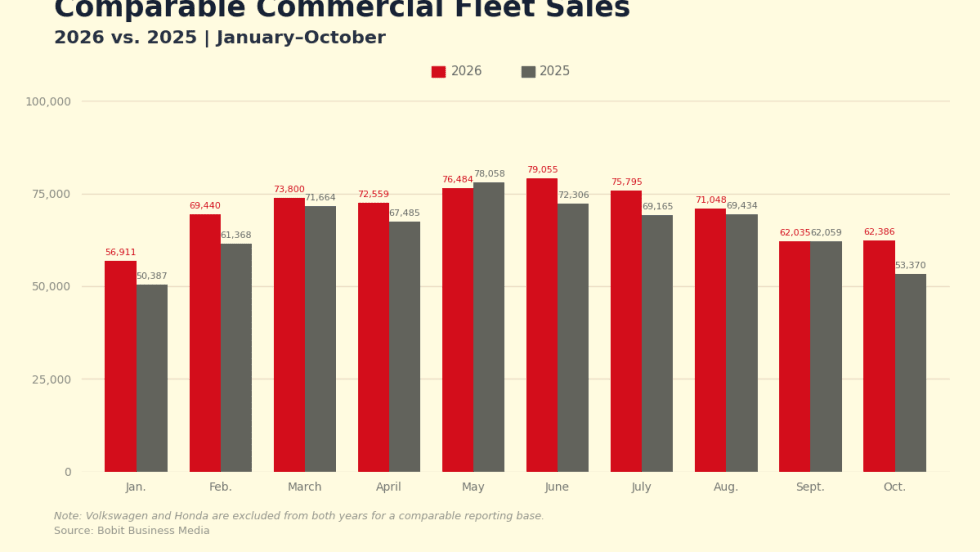
Commercial Fleet Sales Rebound 16.9% Through October
October's stronger results lifted commercial fleet sales growth to 6.7% through the first 10 months of 2026.
Read More →
Which Vehicles Earn Your Fleet’s Vote? Voting Opens for 2027 Fleet Vehicle of the Year
Which vehicles earn your fleet’s vote? Cast your ballot to unlock early access to our analysis of ownership costs across 55 vehicle nameplates.
Read More →
Crash Tests, Catalytic Converter Theft & Fleet Safety | AF News Recap
A stolen catalytic converter can cost a fleet far more than the replacement part. This week, we're exploring how to reduce theft-related risk, what fleet managers learned from live IIHS crash testing, the 2027 Jeep Compass's new safety features, and why supporting original industry reporting matters.
Read More →
2027 Jeep Compass Adds Standard Driver-Assistance Features, Starts at $31,985
The 2027 Jeep Compass adds standard adaptive cruise control across the lineup, along with additional technology and equipment options on select trims.
Read More →
2027 Subaru Outback Adds Base Trim, Lowers Pricing Across Lineup
The 2027 Outback starts at $32,995, with price reductions on several trims and expanded availability of hands-free driver-assistance technology.
Read More →
2027 Toyota Camry Offers Hybrid Powertrain Across Five Grades
The 2027 Toyota Camry is a carryover with new pricing.
Read More →
Chevrolet Updates 2027 Trax and Trailblazer with More Standard Safety Features
Chevrolet is updating two of its smallest SUVs with added driver-assistance technology, redesigned interiors, and revised trim options. The changes could add more safety equipment as standard for commercial fleets, while a new Trailblazer configuration adds another all-wheel-drive option.
Read More →
Hall of Fame Inductee: John Dmochowsky
The longtime Mondelēz International fleet executive joins the Automotive Fleet Hall of Fame.
Read More →
Hall of Fame Inductee: Lee Miller
After more than four decades at Boehringer Ingelheim, Lee Miller leaves a legacy built on fleet expertise.
Read More →