

Current Used-Vehicle Market Conditions and Outlook
Two of the nation’s auction market reports – Manheim’s Used Vehicle Value Index and ADESA’s Analytical Services – each provide a monthly analysis of the used-vehicle market conditions and an outlook commentary.

Two of the nation’s auction market reports – Manheim’s Used Vehicle Value Index and ADESA’s Analytical Services – each provide a monthly analysis of the used-vehicle market conditions and an outlook commentary.
Headquartered in Atlanta, the Manheim Used-Vehicle Value Index applies statistical analysis to a database of more than 5 million annual used-vehicle transactions to measure used-vehicle prices, independent of underlying shifts in the characteristics of vehicles being sold.
Produced at the company headquarters in Carmel, ADESA’s vehicle price analysis is based on the AuctionNet database of nearly six million annual sales transactions from approximately 150 of the largest U.S. wholesale auctions. ADESA Analytical Services segregates the database using the J.D. Power and Associates Vehicle Segmentation Guide to study trends by model class.
The Manheim’s chief ecomomist, Tom Webb, produced this report:September Starts Seasonal Slide
Unarguably, model year changeover is the most tumultuous time of the year for used-vehicle pricing. A pure statistical analysis, after discounting for mix and mileage changes, shows that used-vehicle prices on average slip 4.6 percent during the three-month period of September, October, and November. That decline is on top of the normal 1-2 percent that individual vehicles depreciate on a month-in and month-out basis. Historically, the seasonal slip in prices during October is twice as big as that of September, and this year the impact may be compounded by the high level of ’04 models still in dealer inventory. In addition to moving potential high-end used-vehicle buyers into the new-vehicle market, the high level of carryover stocks depresses used vehicle prices across the spectrum.
Incentives Initiate Month-End Price Slide
New-vehicle incentive spending for the entire month of September was unchanged from August according to data from Autodata. Hidden within that monthly average, however, are the large incentives that the domestic manufacturers applied in the final days of the month. Not surprisingly then, wholesale used- vehicle prices were noticeably weaker towards the end of the month. Indeed, at mid-month, wholesale prices were more than half a percent higher than August, but almost all of the gain was wiped out in the final week and a half of the month. Additionally, September’s month-end weakness was concentrated in the market segments most heavily targeted by the incentive activity, namely, light-duty trucks.
Price Movements by Market Class
Compact cars continue to achieve strong prices with the annual gain now in excess of 11 percent. We would continue to note, however, that a substantial amount of this improvement is due to a richer mix of vehicles being sold within the category — that is, they also had higher transaction prices when sold new.
Wholesale prices for mid-size cars, although still up for the year, fell sharply in September. The segment is coming under some pressure due to an increasing supply of off-rental vehicles.
Luxury car prices, after underperforming in the summer months, picked up in September. The strongest price segment of the wholesale market for September was full-size vans; compact van prices remained weak.
Wholesale prices for all SUVs were down 4.0 percent from their year-ago level. The price changes for the sub-categories of SUVs were: entry-level SUV +1.1 percent, midsize SUV –4.1 percent, large SUV –7.1 percent, and luxury SUV –5.9 percent.
ADESA’S market analysis reported:
The fall market is now in full swing. Typically this means that a large number of vehicles are being cycled back into the market after their first months or years of service as rental and fleet vehicles. In many cases, this is timed to coincide with model-year changeover, although this year that timing was delayed in parts of the country bombarded by hurricanes— including the large Florida rental market.
Based on the September market indicators, sellers generally found a solid market for their vehicles despite mounting auction inventories, slowing retail used-vehicle sales, and high model-year-end-clearance new- vehicle incentives. Perhaps these price-depressing factors were mitigated by the positive price impact of lower off-lease volumes. Still, it would be prudent for remarketers to set price expectations a bit lower when anticipating results for October, as the negative price impacts of higher auction inventories and new vehicle incentives gather a fuller head of steam.
Average auction prices in September were up from year-ago levels for the seventh month in a row, and were modestly higher than in August. According to ADESA Analytical Services’ monthly analysis of Wholesale Used Vehicle Prices by Vehicle Model Class, average auction prices in September were up 1.6 percent from year-ago levels, and 0.1 percent relative to the previous month.
For the third month in a row, compact cars had the strongest year-over-year price gains, and full-size SUVs had the sharpest price declines for the same period. Average prices in both these categories had double-digit, year-over-year movements, though in opposite directions. Although other factors contribute to this trend, the impact of gas prices that have remained at high levels is impossible to ignore.
Retail sales of used vehicles slowed in September. According to data from CNW Marketing/Research, retail used-vehicle sales in September were down 6.3 percent year-over-year — only the second decrease in the last 16 months. Sales by independent used-car dealers fell 3.9 percent, while franchised dealers sold 8.4 percent fewer used vehicles that this time last year. Nevertheless, used-vehicle sales by independent dealers on a year-to-date basis are at their best levels in this decade.
The ADESA Auction Inventory Index was higher than its year-ago level for the third month in a row. The index stood at 136.8 at September month, end-up 6.0 percent from its year-ago level of 129.1. ADESA Analytical Services estimates that this represents approximately 35 days of auction sales- the first month since January that inventories have broken the 30-day mark, and further indication that the traditional fall de-fleeting season is upon us.
The ADESA Auction Dealer Optimism Index registered a modest decline in September. The index measures dealer “optimism” as the year-over-year change in dealer consignment “conversion rates” at ADESA auctions. The September index shows that dealers purchased a slightly lower percentage (-0.7 percent pts) of vehicles offered for sale by other dealers at ADESA auctions than they did during the same period in the prior year and reflect seasonal norms for dealer consignment conversion rates.
More Remarketing
When Should a Fleet Repair Vehicle Damage Before Remarketing?
Not every dent, scratch, or mechanical issue is worth fixing before selling a fleet vehicle. Learn how to weigh repair costs, resale value, market demand, and downtime to determine when reconditioning pays off and when selling as-is makes more sense.
Read More →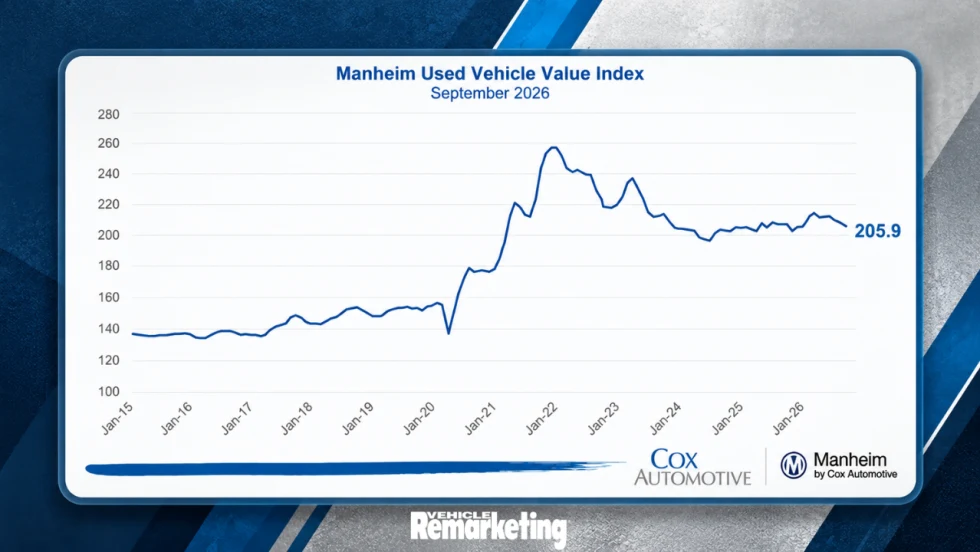
Wholesale Used-Vehicle Values Fall as Cox Automotive Cuts 2026 Forecast
Wholesale used-vehicle prices declined in September as depreciation accelerated, prompting Cox Automotive to lower its year-end forecast.
Read More →
FLD Promotes Three Executives in Leadership Changes
FLD has promoted three longtime executives, naming Gary Mott CEO, Richard Mallek president, and Ron Sanders managing partner.
Read More →
Ford Pro Launches Certified Pre-Owned Program for Commercial Vehicles
Ford Pro Advantage will offer certified pre-owned Class 1-7 commercial vehicles through more than 700 Ford Pro Commercial Vehicle Centers.
Read More →
Copart to Acquire ACV in $1.9 Billion Deal
The acquisition would expand Copart beyond its traditional salvage business into dealer-to-dealer wholesale remarketing while adding ACV’s vehicle data, inspection, and valuation technology.
Read More →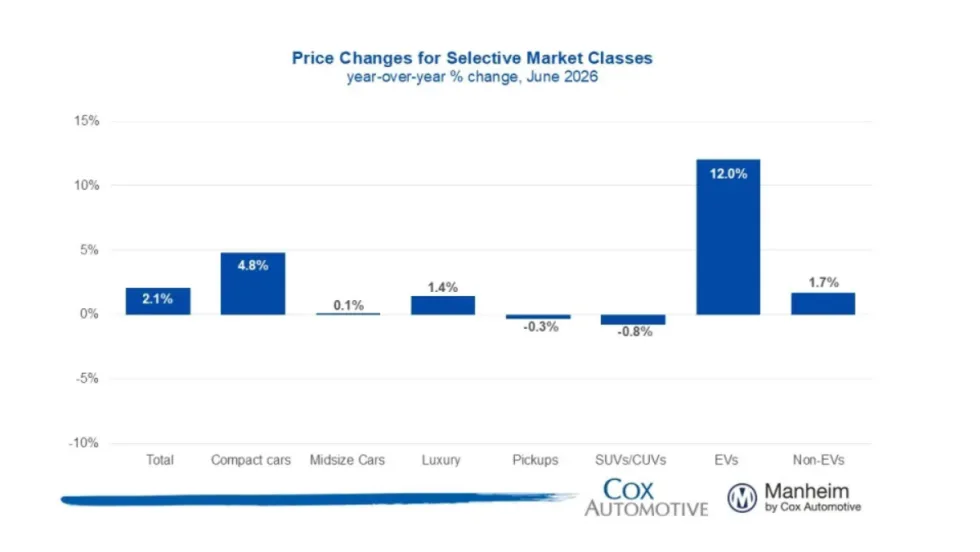
Manheim Index Shows Used-Vehicle Wholesale Prices Up 2.1% in June
The market is seeing stronger appreciation in older used vehicles this year, and the most affordable segments have been among the year’s best performers.
Read More →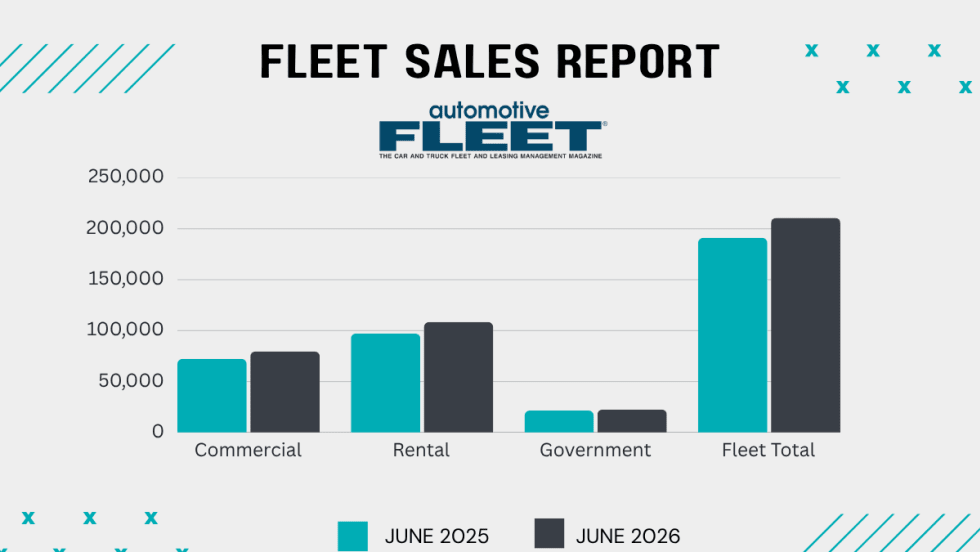
Commercial Fleet Sales Contribute To June, YTD Gains
The fleet sector has boosted its vehicle purchases at a reliable pace in the first half of this year compared with 1H 2025.
Read More →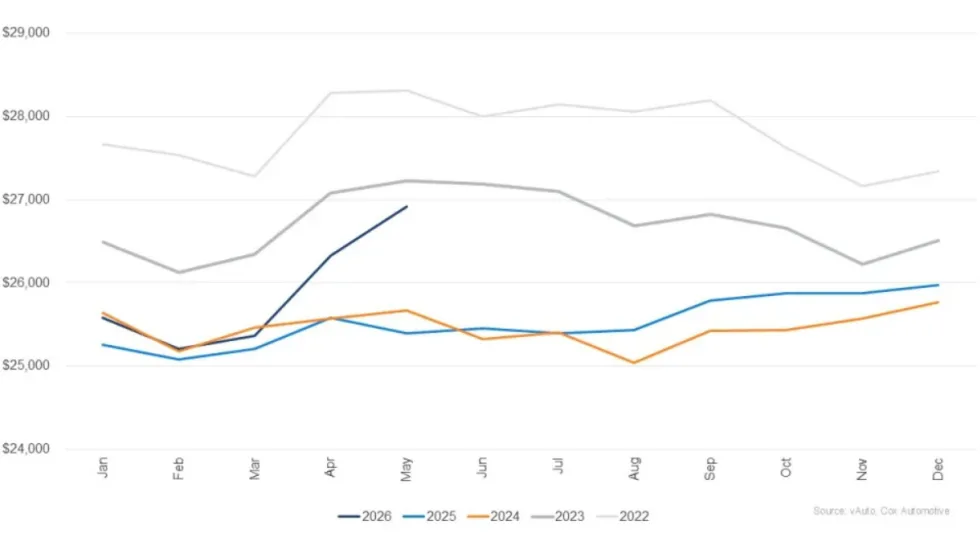
Used Vehicle Prices Climb Higher As Sales Pace Slows
The higher prices at used retail reflect strong wholesale values earlier in the spring, particularly for older, more affordable vehicles.
Read More →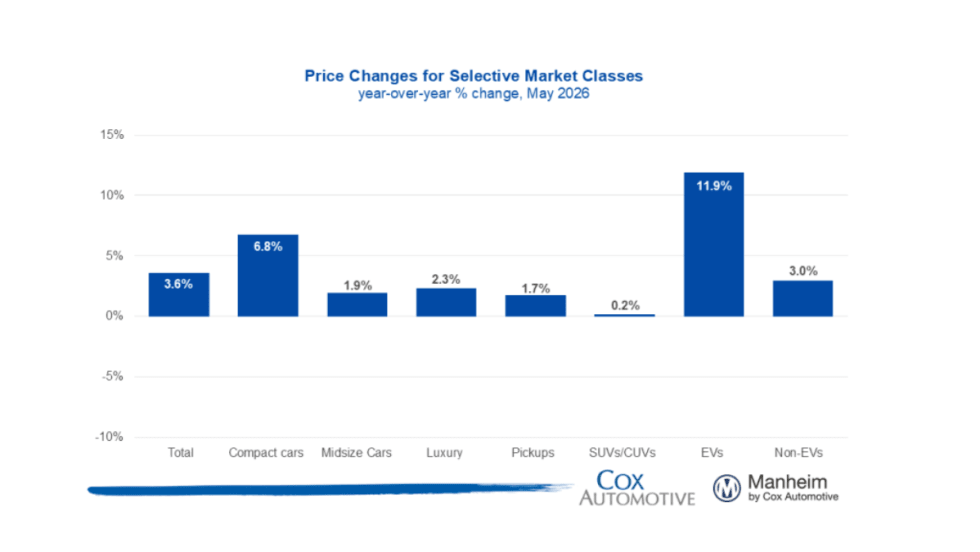
Wholesale Used Vehicle Market Sustains Moderate Rise In Values, Prices
Trends continue to normalize after a strong start to the year, as consumers contend with higher gas prices in the coming summer months.
Read More →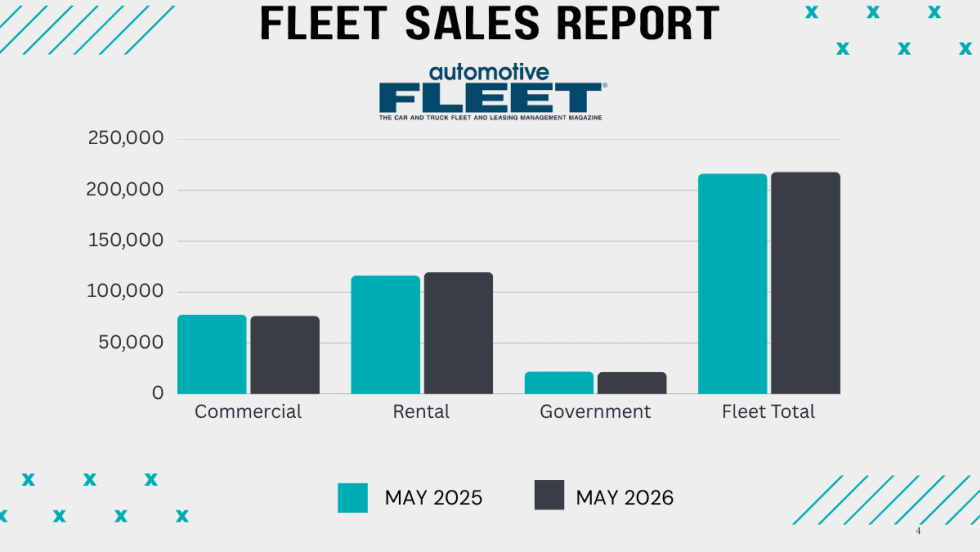
Commercial Fleet Sales Still Lead Sectors Despite May Mini Dip
The U.S. economy's continued growth and positive business investment are creating a favorable environment for fleet vehicle demand.
Read More →