

How Will the War on Terrorism Affect Fuel Prices? Watch Out for Price Volatility as the War Enters Its Later Phases
It took less than an hour-and-a-half after the terrorist attacks of Sept. 11 before reports began to surface of price gouging by gasoline stations in California, Illinois, Indiana, Michigan, North Dakota, and Oklahoma. Some stations were charging as much as $5 a gallon before the state attorney generals stepped in and threatened to sue for consumer fraud.

It took less than an hour-and-a-half after the terrorist attacks of Sept. 11 before reports began to surface of price gouging by gasoline stations in California, Illinois, Indiana, Michigan, North Dakota, and Oklahoma. Some stations were charging as much as $5 a gallon before the state attorney generals stepped in and threatened to sue for consumer fraud.
But this was not a glimpse of things to come.
As of this writing, the events of Sept. 11 and subsequent retaliation in Afghanistan have actually contributed to a decrease in fuel demand. Presently, there is an oversupply of aviation fuel, the supply of gasoline is higher than last year's stock levels, and the pre-existing slowdown in the U.S. economy has lowered overall demand for fuel by industrial users.
However, it is the probability of expanded U.S./coalition military operations and potential counter-strikes by terrorists that threaten to increase pricing volatility over the next few years, especially if the war expands in its later phases to Iraq or other oil-producing countries identified as supporting terrorist activities. This has a probability of disrupting the flow of oil, which will impact the U.S., since currently more than half of our daily petroleum supply is imported. In addition, large-scale military activities beyond Afghanistan for sustained periods would divert fuel supplies away from consumer use. This would add a new demand element for oil supplies as the U.S. and coalition militaries consume higher-than-normal quantities of fuel.
There is precedent for making these statements. From 1973 to 2001 there have been five major escalations of gasoline prices - all but one the result of wars. There were the Arab oil embargo in 1973 following the Mideast war of that year, the Iranian revolution in 1978, the Iran and Iraq war in 1980, and the Gulf War in 1990. The fifth run-up in prices occurred in 1999 following the simultaneous OPEC production cuts and the increased demand for fuel from Asian economies recovering from recession.
Although the U.S. Department of Energy has not increased the supply of oil for the Strategic Petroleum Reserve, which currently holds 564 million barrels of oil in four sites in Texas and Louisiana, oil analysts do not regard this as a sign of near-term fuel stability. Rather they view it as a manifestation of bureaucratic delay and uncertainty. Congressional initiatives are underway to increase the number of barrels in the Reserve, which, short-term, would represent another new demand element for oil supplies.
The Near-Term Concern is Refining Constraints
What complicates matters are the pre-existing weaknesses in our fueling infrastructure. Regulations and public pressure are such that it has been impossible to build an all-new refinery in the U.S. since mid-'70s. This has resulted in limited refining capacity, especially for the production of reformulated gasoline, which has increased the frequency of spot shortages. For instance, California fuel prices are volatile because there are few sources of its unique blend of gasoline outside the state. California refineries need to be running at near full capacity in order to meet the state's fuel demands. If more than one of its refineries experiences downtime at the same time, California's gasoline supply becomes very tight and prices soar, as when a fire occurred at a Tosco refinery in the Los Angeles area in April 2001. Another example of our limited refining capacity occurred in the Midwest in the summer of 2001. One of the key factors that led to the run-up in gas prices, which topped $2 per gallon, was that the Midwest uses ethanol reformulated gasoline. Few refineries outside the Midwest produce this reformulation, making the Midwest vulnerable to price spikes when supply problems occur, especially during the summer when inventories are at their lowest.
However, not all fleets will be affected by pricing volatility. Retail gasoline prices tend to be higher in certain states than others. For instance, the least-expensive gas prices are usually in Atlanta because Georgia has the lowest taxes on gasoline in the country. In addition, your proximity to oil supplies also influences retail prices. For example, the areas farthest from the Gulf Coast (the source of nearly half of the gasoline produced in the U.S.) tend to have higher prices than those that are closer. Plus, if you operate vehicles in areas where reformulated gas is mandated, the cost, on average, is 3 to 5 cents more per gallon than conventional gasoline.
Roller Coaster-like Volatility
Secretary of Defense Donald Rumsfeld has described our current political/military situation as being analogous to a game of billiards. He said, "When you hit a cue ball it is difficult to predict how the other balls will careen." Although there is no predicting how fuel prices will careen in the future, my assessment is that all the necessary ingredients are in place for us to experience a recurring roller coaster-like volatility of peaks and valleys in the price of fuel.
Let's hope that I'm wrong.
More Operations
90% Use Telematics. Are Fleets Getting Safer? | AF News Recap
This week, we're breaking down which industries have the highest rates, how Jamie McKay manages 2,400 vehicles, what's happening with the 2027 fleet awards, and why software-defined vehicles could introduce new costs.
Read More →
What's Best Handled by an FMC, and What's Better Done Directly?
Fleet managers continue to rely on FMCs for essential services but are taking a closer look at where working directly with suppliers can improve efficiency and responsiveness.
Read More →
Fleet Meets: Erin Gilchrist
Meet Erin Gilchrist, the inaugural Mike Antich Spirit of Fleet Award winner, as she shares insights on leadership, mentorship, the power of industry connections, and why people remain at the heart of fleet's future.
Read More →
How 2026 Fleet Visionary Jamie McKay Manages 2,400 Vehicles Across 37 States
How do you keep 2,400 vehicles running across 37 states? Fleet Visionary Award winner Jamie McKay shares how collaboration, flexibility, and a few simple strategies help her tackle fleet management challenges at Aptive Pest Control.
Read More →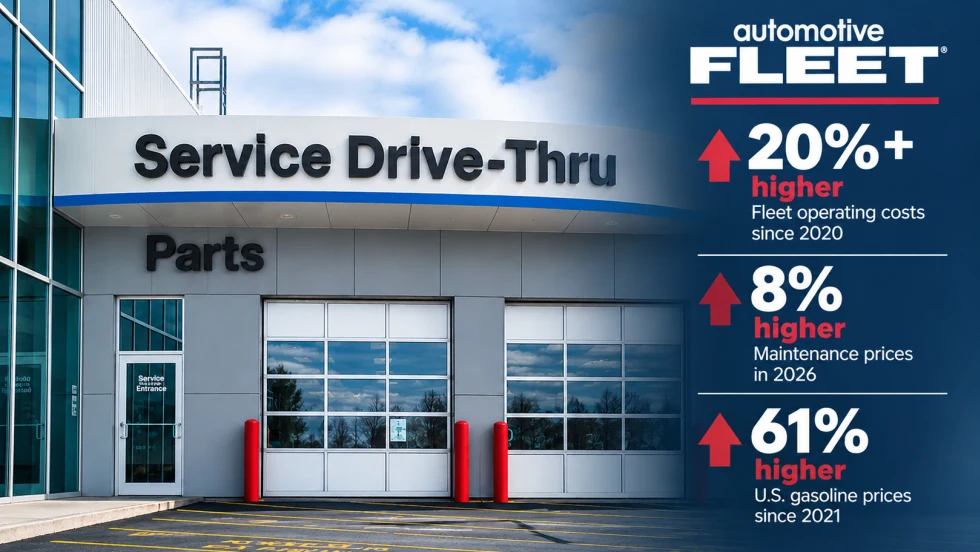
Managing Fleet Costs in an Era of Permanent Volatility
Fleet operating costs have risen more than 20% since 2020, raising a key question: When does extending a vehicle's service life stop making financial sense?
Read More →
The Next Evolution of Fleet Management: Autonomous Operations
This opening keynote session at the Fleet Forward Conference highlights the future of autonomous driving for fleets.
Read More →
How to Reduce the Total Cost of Risk From Catalytic Converter Theft
A stolen catalytic converter can cost fleets far more in downtime and lost productivity than in repairs. A total-cost-of-risk approach can help fleet managers quantify their exposure and prioritize theft prevention.
Read More →
Personal-Use Charges Rise as Vehicle Values Fall | AF News Recap
Personal-use charges are climbing, wholesale used-vehicle values are declining, and commercial fleet sales growth is slowing. This week, we're breaking down the latest fleet data, plus how Element Fleet Management is helping Waymo prepare for its first Canadian robotaxi market.
Read More →
Here's When You Should Make an Exception to Fleet Policy
Fleet policies are designed to create consistency, but not every driver or situation fits neatly within standard rules.
Read More →
AI-Native or AI-Acquired: What Should Fleet Managers Look for in an AI Platform?
Six questions can help fleet managers look beyond AI marketing claims to evaluate integration, data access, and real-world operational performance.
Read More →