

How to Determine the Correct Depreciation Reserve
The open-end TRAC lease is an excellent tool for fleet managers to manage depreciation expense. However, maximizing its effectiveness is based on properly establishing a depreciation reserve. Here’s how to do it.
It is one of the most creative and unique financial instruments in managing a vehicle fleet. The open-end TRAC lease has been a staple in the fleet industry for decades. (TRAC is an acronym for “terminal rental adjustment clause.”) However, the basic principles of the TRAC lease sometimes are misunderstood.
A basic tenet of accounting is matching expense to the time period in which it occurs. Open-end TRAC leases enable fleet managers to do so, but only if the various terms in the lease are understood and applied correctly.
Defining Terms
The first step in creating a proper
depreciation reserve is to know and understand the various components
of the open end TRAC lease. These components are often wrongly used interchangeably.
First, what is a TRAC? It is merely a clause that states that at the point when a lessee decides to terminate a particular vehicle’s lease, the following occurs:
The lessor sells the vehicle.
If the proceeds exceed a predetermined value, the excess is returned to the lessee.
If the proceeds fall short of that pre-determined value, the lessee makes up the difference to the lessor.
Thus, the “terminal rental adjustment” is one of three things: zero (in a case where the proceeds are exactly the same as the value), an additional lease payment by the lessee (where the proceeds are less than the value), or a credit back to the lessee (where the proceeds exceed the value).
Several primary terms are used in any discussion of the depreciation component of a TRAC lease:
Amortization. This is the rate at which the principal of a loan is reduced to zero over the loan period. In the case of a TRAC lease, vehicle cap costs are amortized over a period of months, in equal increments, toward the goal of matching the unamortized amount at replacement with the vehicle’s market value.
Depreciation. Depreciation is simply the difference between the original cost of a fixed asset and the proceeds from the sale of the asset. Depreciation, therefore, cannot be determined until after the asset is sold, often called “actual depreciation.”
Depreciation Reserve. In a TRAC lease, each month’s payment contains a repayment of principal, a portion of the original cost, similar to the repayment of a loan. These payments accumulate into a reserve for the anticipated depreciation of the vehicle when it is finally sold.
“Book Value.” The so-called book value of a vehicle in a TRAC lease is the portion of the cap cost that remains after amortization payments have been paid. Also called the “unamortized” book value. It is this value against which the resale proceeds are applied to determine the terminal rental payment under the TRAC.
The TRAC: How Does It Work?
In the majority of fleet leases, the “predetermined value” is agreed upon at inception. The lessee and lessor concur on the rate at which the vehicle’s original cost (“capitalized) cost”) is reduced or amortized. In theory, at this rate, the actual (market) value declines over time, so when the vehicle is sold, the remaining value matches the vehicle’s actual value on the open market. In effect, a portion of each lease payment is set aside — reserved — to cover the depreciation that inevitably occurs as the vehicle ages and mileage accumulates.Here is an example. Let’s assume the vehicle’s cap cost is $20,000. The lessee (fleet) has a replacement policy that states vehicles are replaced at 36 months or 70,000 miles, whichever occurs first. The vehicle in question will be driven 2,400 miles per month; thus, under the policy, replacement is anticipated after 29 months in service (having reached the 70,000 mile criterion before the 36-month limit).
Further, the fleet anticipates at that point, the vehicle will have a market value of $8,400. Ideally, then, the lease (predetermined) value, against which the actual sale proceeds will be applied, should be $8,400, after 29 lease payments are made. The open-end TRAC lease accomplishes this by amortizing the original cap cost at a rate so that at replacement, the unamortized (book) value reflects the market value:
Cap Cost: $20,000
Reserve rate: 2% (50 months or $400/month)
Time in service: 20 months
Total reserve: $8,000 (20 x $400 = $8,000)
Unamortized value at resale: $12,000 ($20,000 - $8,000 = $12,000)
Resale proceeds: $9,800
TRAC adjustment: $2,200 to the lessor ($12,000 - $9,800 = $2,200)The vehicle’s original value clearly is not being amortized at a rate that properly reflects the rate at which the vehicle actually depreciates on the marketplace. If the fleet manager adjusts the reserve rate to, say 40 months, the calculation would look like the following:
New reserve rate: $500 / month ($20,000 / 40 months = $500)
New total reserve: $10,000 ($500 x 20 months = $10,000)
New TRAC adjustment: $200 credit to the lessee ($10,000 - $9,800 = $200)By making this adjustment, the fleet manager has considered the faster rate of actual depreciation on these vehicles and increased the rate at which the reserve is accumulated. The result is an unamortized value that more accurately reflects the vehicle’s actual market value at termination. This action avoids large cash flow outward at the end of the lease, facilitates budgeting, and better matches the realization of the expense with the time in which it occurs (making the company’s auditors more comfortable with the transaction).
It will, of course, be impossible to tune the reserve rate finely enough to approach an average TRAC adjustment to zero; nor is it necessary, as the vagaries of the used-vehicle marketplace make this nearly impossible. A brief discussion with the company’s auditors or the accounting department will give the fleet manager an idea of an acceptable TRAC adjustment level. Achieving an adjustment within $500 each way, for example, would appear more acceptable than adjustments of thousands of dollars and more reflective of the actual timing of the expense.
There is a downside, based in the time value of money. In the example, vehicles for which the reserve rate amortizes the value too slowly (to match the market) suffer a $100/month “hit” in cash flow. As the remedy, increasing the rate increases the monthly depreciation reserve (and thus the lease payment) by that amount.
Further, the TRAC adjustment is made 20 months after the lease inception in less valuable dollars. The effect is limited, however, since the additional reserve is similarly discounted over time. At any rate, the purpose of the TRAC isn’t to maximize cash flow or delay the booking of expense. It is to allow the fleet to recognize the expense as it occurs, while retaining the flexibility to do so for vehicles of widely varying usage.
Establishing The Policy
The sample fleet had a number of differing vehicle usages, resulting in several different results when the TRAC adjustment is made. A single reserve rate for the entire fleet thus is difficult to justify. Most of the issue lies in mileage. The faster mileage accumulates, the more quickly a vehicle is replaced under the time/mileage policy, and the faster its value declines in the open market.It becomes incumbent upon the fleet manager, after reviewing the data, to adjust the reserve rates for different vehicle classes. In the sample fleet, the 50-month, 2-percent per-month rate is acceptable for more than half the fleet (500 units sold). For the 400 units for which mileage accumulates more quickly, a reserve rate of 40 months (2.5 percent per month) reduces the original value more accurately, and the existing TRAC adjustment average of $2,200 is reduced to $200.
The third class of vehicle, those for which mileage accumulates more slowly and time in service is lengthened, can be viewed either as exceptions and treated on a case-by-case basis or, if the exceptions are consistent, the reserve can be adjusted so that less is reserved each month and the unamortized value is higher at replacement.
Whatever the specifics of any particular fleet’s circumstances, the basics of establishing the proper depreciation reserve remain the same.
Know the definitions of depreciation, depreciation reserve, and amortization and how they interact within the lease transaction.
Keep historical data on resale experience.
Break the resale data down into categories of usage and calculate averages for the TRAC adjustments.
When categories remain consistent, adjust the depreciation reserve according to resale experience; up for vehicles experiencing large credits upon resale (proceeds exceed unamortized value), down for units that see large payments to the lessor (proceeds fall short of unamortized value).
Discuss with the accounting or finance department acceptable adjustment levels for purposes of matching expense to time incurred.
Treat exceptions on a case-bycase basis.
Monitor resale and TRAC adjustment experience going forward and adjust as necessary.
More Operations
90% Use Telematics. Are Fleets Getting Safer? | AF News Recap
This week, we're breaking down which industries have the highest rates, how Jamie McKay manages 2,400 vehicles, what's happening with the 2027 fleet awards, and why software-defined vehicles could introduce new costs.
Read More →
What's Best Handled by an FMC, and What's Better Done Directly?
Fleet managers continue to rely on FMCs for essential services but are taking a closer look at where working directly with suppliers can improve efficiency and responsiveness.
Read More →
Fleet Meets: Erin Gilchrist
Meet Erin Gilchrist, the inaugural Mike Antich Spirit of Fleet Award winner, as she shares insights on leadership, mentorship, the power of industry connections, and why people remain at the heart of fleet's future.
Read More →
How 2026 Fleet Visionary Jamie McKay Manages 2,400 Vehicles Across 37 States
How do you keep 2,400 vehicles running across 37 states? Fleet Visionary Award winner Jamie McKay shares how collaboration, flexibility, and a few simple strategies help her tackle fleet management challenges at Aptive Pest Control.
Read More →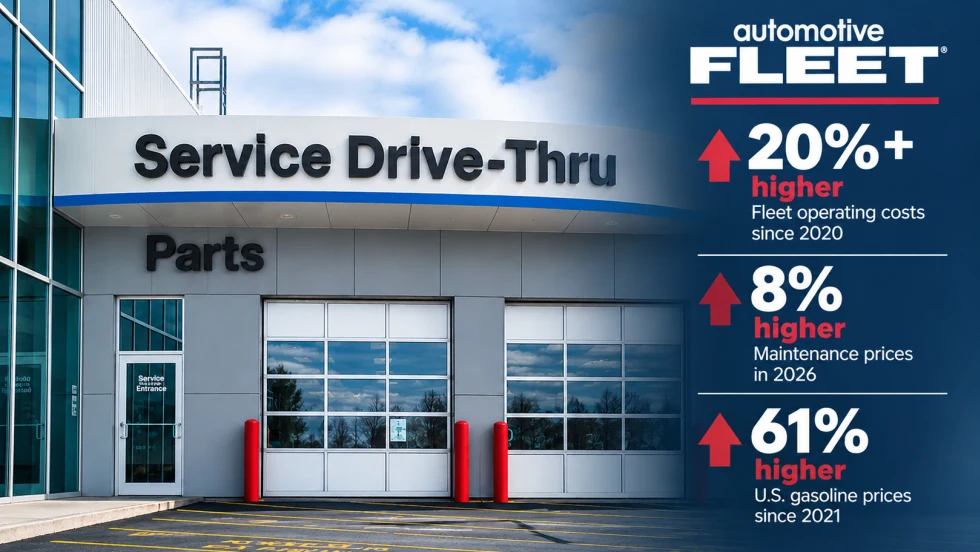
Managing Fleet Costs in an Era of Permanent Volatility
Fleet operating costs have risen more than 20% since 2020, raising a key question: When does extending a vehicle's service life stop making financial sense?
Read More →
The Next Evolution of Fleet Management: Autonomous Operations
This opening keynote session at the Fleet Forward Conference highlights the future of autonomous driving for fleets.
Read More →
How to Reduce the Total Cost of Risk From Catalytic Converter Theft
A stolen catalytic converter can cost fleets far more in downtime and lost productivity than in repairs. A total-cost-of-risk approach can help fleet managers quantify their exposure and prioritize theft prevention.
Read More →
Personal-Use Charges Rise as Vehicle Values Fall | AF News Recap
Personal-use charges are climbing, wholesale used-vehicle values are declining, and commercial fleet sales growth is slowing. This week, we're breaking down the latest fleet data, plus how Element Fleet Management is helping Waymo prepare for its first Canadian robotaxi market.
Read More →
Here's When You Should Make an Exception to Fleet Policy
Fleet policies are designed to create consistency, but not every driver or situation fits neatly within standard rules.
Read More →
AI-Native or AI-Acquired: What Should Fleet Managers Look for in an AI Platform?
Six questions can help fleet managers look beyond AI marketing claims to evaluate integration, data access, and real-world operational performance.
Read More →