

Ed Bobit's Publisher's Page
As expected (and already accepted) the Investment Tax Credit (ITC) is out as of January 1, 1986.

If Patrick Henry thought that taxation without representation was bad, he should see how it is with representation.-The Old Farmer's Almanac
The income tax has made more liars out of the American people than golf has. Even when you make a tax form out on the level, you don't know when it's through if you are crook or a martyr.-Will Rogers
What is the difference between a taxidermist and a tax collector? The taxidermist takes only your skin. -Mark Twain
Knowing full well that the new tax overhaul legislation is now imminent following final approval from the joint Senate/House Committee, and with only the Wall Street Journal's First-day analysis to guide me, here's my rundown of the bill's direct impact on those engaged in the fleet business.
As expected (and already accepted) the Investment Tax Credit (ITC) is out as of January 1, 1986. Those lessors who have included ITC value into previous price calculations could be hurt by the retroactive effect from a tax standpoint; some estimates indicate as much as a $22-per-month adjustment for a $12,000 vehicle. Depending on the "tax appetites" of certain lessors, there were mixed feelings on the loss of ITC, but at least now lessors have a better idea how to set and relate marketing objectives for the immediate future. Association lobbyists worked hard to delay the effective date to the beginning of '87' like most of the new tax bill, but that provision did not carry through.
During these past months, the issue of depreciation for cars probably received the greatest lobbying focus by industry leaders. One of their chief concerns centered on the possibility of having to calculate the minimum tax (Alternative Minimum Tax-AMT) using straight line depreciation over five years. While virtually the entire industry preferred three year depreciation for both AMT and regular tax purposes, industry leaders pushed next for at least an acceleration formula in any five-year AMT plan. This is what we apparently now have. For regular tax purposes, depreciation will be over a five year period at 200 percent declining balance. For calculating the 20 percent AMT, depreciation will also be over five years, but with 150 percent declining balance.
The accompanying chart, developed by Paul R. Doyle C.P.A, tax counsel for the National Vehicle Leasing Association, may aid in the initial understanding of the calculations (unless Congress or the IRS come up with modifications).
From a macro perspective, knowing that we now have to be fully concerned about paying a minimum tax, the result is a negative impact compared to current law. But to the extent that the new calculation for AMT minimizes the amount of the preference, it's good for the industry. The five-year/200 percent declining balance for regular tax depreciation is less than the industry would have liked compared to current law, but it's still acceptable to our market.
TAX YEAR | 200% | 150% |
1* | 20% | 15% |
2 | 32 | 22.5 |
3 | 19.2 | 17.85 |
4 | 11.5** | 16.66** |
5 | 11.5 | 16.66 |
6* | 5.8 | 8.33 |
* half year "convention" - IRS presumes initial purchase is made mid-year; i.e. 20% in first year is half of 40% allowed.
** Switch over to straight line, assuming IRS permits it.
Reaction is expected to be much more positive to the consumer interest deductions for car loans (plus boat loans, credit cards, etc) as they are phased out, Sixty percent of such interest will be disallowed in 1988. Coupled with rising consumers demand for leasing this provision could have a dramatic impact on an individual's "buy vs. lease" decision. While few people currently are sophisticated enough to actually realize the tax benefits during such a buy/lease purchase decision, there is every reason to believe that the enterprising consumer lessors will make certain that they become more knowledgeable for their evaluations.
Overall, the new tax bill should create a positive impact on leasing. For one thing, we know what the rules are; no more waiting or indecision. While tax considerations will always be a part of any capital goods acquisition, there is good reason to believe that decisions will now be more economically motivated for leasing vs. ownership vs. employee reimbursement.
The net, net result is that most would have been happier with the current laws, but considering the political and governmental financial environment the industry came out pretty well.
If could have been a lot worse.
More Operations

Fleet Has a Talent Pipeline Problem. What Comes Next? | AF News Recap
Where will fleet’s next generation of leaders come from? This week, we’re looking at the industry’s talent pipeline, what certification can add to a fleet career, how to build an award-worthy track record, and the return of Automotive Fleet’s Personal Use Survey.
Read More →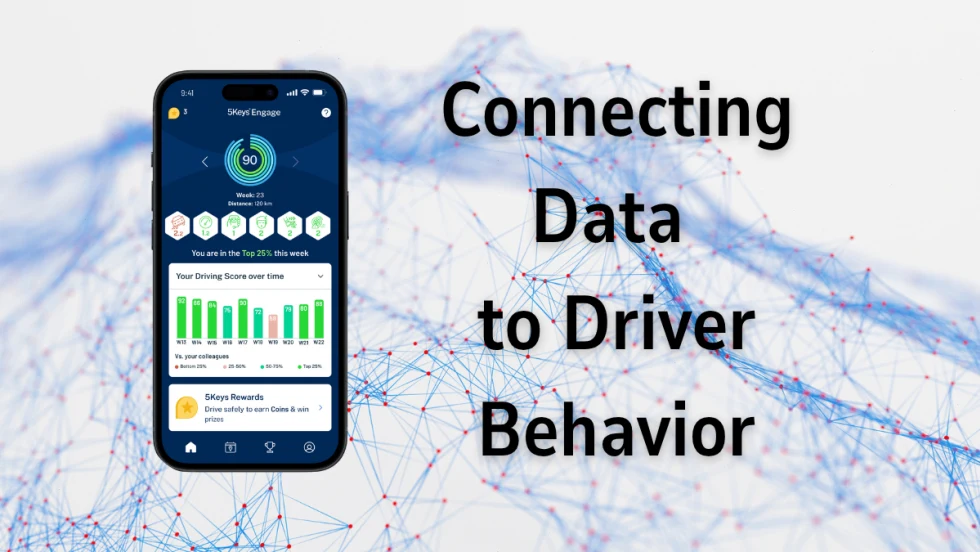
Smith System Launches Driver Risk Management Program
Fleets have more driver data than ever, but identifying risky behavior doesn't necessarily correct it. Smith System's new Driver Risk Management program combines monitoring, training, and follow-up coaching to help fleets connect risk signals with driver intervention.
Read More →
Automotive Fleet Opens 2026 Personal Use Survey for Commercial Fleet Managers
Less than two weeks left! Commercial and corporate fleet managers are invited to share how their organizations handle company vehicle personal-use policies, charges, and driver eligibility.
Read More →
From AI Prompts to AI-Generated Safety Songs | AF News Recap
Can better prompts make AI more useful for fleet managers? This week, we’re breaking down smarter fleet analysis, an AI-assisted experiment that turned safety training into music, and what happened to fuel prices in August.
Read More →
How to Write Better AI Prompts for Fleet Analysis
Include these six elements in your fleet prompts to generate more relevant analysis and accurate answers.
Read More →
Fleet Meets: Eric Kilgore
This edition of the Fleet Meets series features one of the industry's best leaders driving multi-market and national operations.
Read More →
Why Reactive Fleet Management Is Becoming Too Expensive to Sustain
Research highlights a growing need for proactive management strategies to address rising costs in fleet operations effectively.
Read More →
What Your Fleet KPIs Aren’t Telling You
Tracking fleet metrics is only useful when the data leads to better decisions. This guide helps fleet leaders assess cost, utilization, and downtime more accurately, identify performance gaps, and prioritize the actions that can improve operational results.
Read More →
Hidden in Plain Sight: Fleet Compliance Risks
Fleet compliance isn't just about having policies — it's about consistently enforcing them. This practical guide reveals six hidden compliance risks common in public sector and shared fleet operations and outlines proven strategies to improve visibility, accountability, and audit readiness
Read More →
Turning Fleet Payment Data into Executive Insights
Does data alone drive results in operations?
Read More →