

Ed Bobit's Publisher's Page
The following was presented on December 19.1983, in Jackson, MS, at a congressional hearing by the Subcommittee on Commerce, Transportation, and Tourism regarding H.R. 1415 (fleet allowances) and chaired by Rep. James J. Florio (D-NJ).

The following was presented on December 19.1983, in Jackson, MS, at a congressional hearing by the Subcommittee on Commerce, Transportation, and Tourism regarding H.R. 1415 (fleet allowances) and chaired by Rep. James J. Florio (D-NJ). Testimony was prepared and presented by Edward J. Bobit as editor and publisher of Automotive Fleet and executive director of the Automotive Fleet and Leasing Association. The initial consideration on H.R. 1415 requires that we focus on the intent of this proposed legislation and the obvious results and effects if it is mandated.
Some identify it as a salvation for consumers which will yield monetary cost savings to retail car buyers; some see it as plugging the gap of discounted purchases by the relatively few privileged fleet buyers; and others have analyzed the bill's meaning as a way to provide auto dealers with an immunity from competitive market forces within a protective restrictive structure. For total clarity, we should be certain to separate "methods of distribution" vs. "the distribution system."
For the record, fleets are not subsidized; they earn discounts or allowances through factory incentives for their volume purchases. This follows a traditional American business practice that is typified by the dealerships themselves when they buy volume amounts of motor oil, filters, undercoating sealant, or tune-up kits.
Fleets are not subsidized with advertising support; fleet ad support is not dissimilar to factory co-op support for the dealership rent-a-car Yellow Page ads.
Dealers are currently protected from unfair price discrimination through the power of the Robinson-Patman Act. H.R. 1415 would be tantamount to protecting dealers from price competition enabling them to formulate prices as well as the terms and conditions surrounding the sale and distribution of the product. Every fleet car is now sold through a dealer, and there is an abundance of dealers seeking current fleet business. Nearly a quarter of the 5,400 Chevrolet dealers and one-half of the Ford Division dealers have indicated to their factories that they are interested in and capable of competing for some phase of the fleet market. Hertz, alone, will utilize the services of over 500 separate fleet-minded dealers with their recently announced intention of purchasing 153,840 cars for the 1984 model year. These fleet-minded dealers find this business profitable or they wouldn't participate, and they negotiate on their own terms. This fleet business is optional but, importantly, open to every dealer in the country. Proctor and Gamble will document that selling private brand products, in addition to their name brands, supports the capital investment amortization of manufacturing equipment, gains volume buying discounts on raw materials, and permits economies in pricing of their brand name products giving the consumer the ultimate benefit of the lowest cost possible. Accounting for one of every five cars sold, fleets also create positive economic consequences for the auto makers. In some cases, over one-third of the year's fleet buying intentions are known to the factories by announcement date in the fall. Deliveries are sensibly spaced throughout the year. An example was in 1982 when the peak month for deliveries was December with 12.2 percent; June was 10.4 percent and even July had 8.4 percent of the total deliveries. This kind of planning allows the factories to establish efficient production schedules to maximize appropriate allocation of costs and resources. It also blends with labor contracts on work force flow and commitment with all factors leading to lower costs for every car built and sold.
In recent years the auto makers suffered a significant loss in total fleet sales when the average age of replacement grew from 24.3 months in the mid-'70s to a current figure of nearly 31 months for leased cars. In this same time period, daily rental cars advanced from a turnover of 12.6 months to the current 16.8 months. Comparably, America's average retail buyer of a new car now holds it for four years. Passage of H.R. 1415, eliminating incentives, portends longer replacement cycles for both lessors and rental operators. This translates into lower factory production with the higher overall costs to be passed along to every new car buyer. It also means higher costs to the consumer renting a car and to the corporate accounts furnishing cars to their employee drivers. Using Automotive Market Report's midwest zone wholesale auction figures for "clean" sedan models in November 1983, and using three popular fleet models (Chevrolet's Reliant) we find there is a depreciation cost range on respective '81 year models of $1,733 to $2,771 from the maker's published base cost pricing for new models. On '82 year models the range is $1,710 to $2,287. If H.R. 1415 becomes law, you can bet the farm that the professional fleet buyer, who makes his purchases rationally, is going to opt for the car with the best resale value not having any allowances to consider.
Beyond that obvious impending result, there are other models and other car divisions that may not qualify even one nameplate on key fleet selector lists. Furthermore, with the traditional extraordinarily high resale values of Japanese imports, the domestic makers will face the ultimate threat of losing a substantial amount of fleet orders when the voluntary import restrictions are rescinded.
If we are truly interested in the lower-cost car for the American consumer, then let the dealers show good faith by divorcing themselves from finance and insurance reserves, sometimes called "kick-backs," and shun the factory sponsored incentive trips to Hawaii or the Bahamas.
Fleet incentives are a viable solution to volume purchases in the American tradition. Passage of H.R. 1415 would not only hurt the consumer directly but would be disruptive and more costly to both fleets, themselves and the auto makers.
More Operations

Fleet Has a Talent Pipeline Problem. What Comes Next? | AF News Recap
Where will fleet’s next generation of leaders come from? This week, we’re looking at the industry’s talent pipeline, what certification can add to a fleet career, how to build an award-worthy track record, and the return of Automotive Fleet’s Personal Use Survey.
Read More →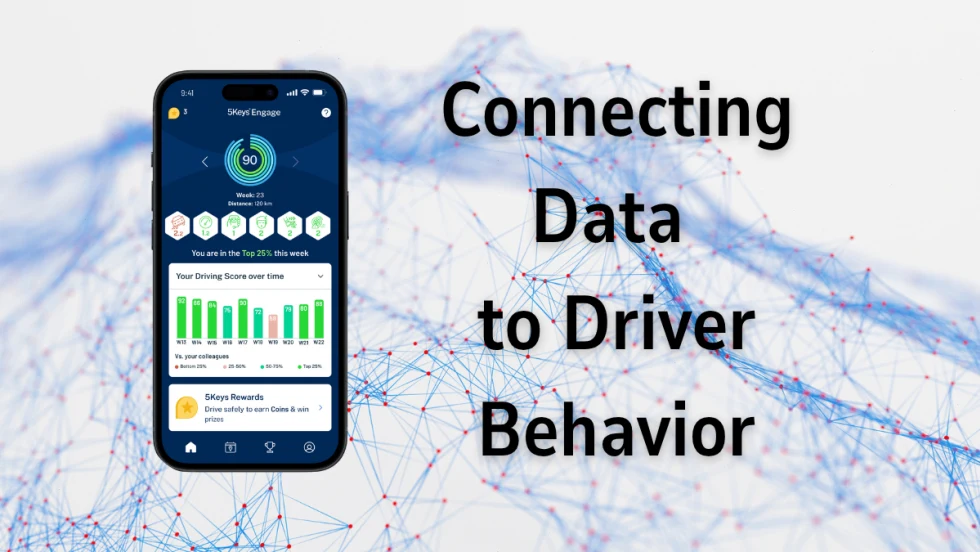
Smith System Launches Driver Risk Management Program
Fleets have more driver data than ever, but identifying risky behavior doesn't necessarily correct it. Smith System's new Driver Risk Management program combines monitoring, training, and follow-up coaching to help fleets connect risk signals with driver intervention.
Read More →
Automotive Fleet Opens 2026 Personal Use Survey for Commercial Fleet Managers
Less than two weeks left! Commercial and corporate fleet managers are invited to share how their organizations handle company vehicle personal-use policies, charges, and driver eligibility.
Read More →
From AI Prompts to AI-Generated Safety Songs | AF News Recap
Can better prompts make AI more useful for fleet managers? This week, we’re breaking down smarter fleet analysis, an AI-assisted experiment that turned safety training into music, and what happened to fuel prices in August.
Read More →
How to Write Better AI Prompts for Fleet Analysis
Include these six elements in your fleet prompts to generate more relevant analysis and accurate answers.
Read More →
Fleet Meets: Eric Kilgore
This edition of the Fleet Meets series features one of the industry's best leaders driving multi-market and national operations.
Read More →
Why Reactive Fleet Management Is Becoming Too Expensive to Sustain
Research highlights a growing need for proactive management strategies to address rising costs in fleet operations effectively.
Read More →
What Your Fleet KPIs Aren’t Telling You
Tracking fleet metrics is only useful when the data leads to better decisions. This guide helps fleet leaders assess cost, utilization, and downtime more accurately, identify performance gaps, and prioritize the actions that can improve operational results.
Read More →
Hidden in Plain Sight: Fleet Compliance Risks
Fleet compliance isn't just about having policies — it's about consistently enforcing them. This practical guide reveals six hidden compliance risks common in public sector and shared fleet operations and outlines proven strategies to improve visibility, accountability, and audit readiness
Read More →
Turning Fleet Payment Data into Executive Insights
Does data alone drive results in operations?
Read More →