

Ed Bobit's Publisher's Page
Fleet managers are people. People have an inalienable right to change their minds. But a consistent change of opinion calls for careful examination and the reasons for it.

If you want to understand today you have to research yesterday.-Pearl Buck
When we think of the past, we forget the fools and remember the sages. We reverse the process for our own time.-George Boas
If three people say you are an ass, put on a bridle.-Spanish Proverb
Fleet managers are people. People have an inalienable right to change their minds. But a consistent change of opinion calls for careful examination and the reasons for it.
Take a moment to study the two charts belowthat are factual statistics covering the actual purchase/registration track record for fleets as reported by domestic makers and the two largest lessors over a period of the last four years. The "factory" chart indicates that during this period there really has not been as dramatic a change in purchases as some would have you believe. The luxury- and standard-size cars lost a few points to the intermediate and compact segments.
In reviewing the lessor chart (which includes "sports models" within the various group headings) there has actually been a notable drop in intermediates and a very strong increase in the compact segment. One might surmise that these lessors primarily service larger fleets and these results may not correspond with the thousands of smaller fleets buying. Perhaps.
Another dichotomy exists in the National Assn. of Fleet Administrator's Annual New Car Buying Survey conducted early each fall on their members' buying intentions. These managers should possess a nearly precise idea as to what will be purchased since they have studied the makers' new product entries, reviewed their lessor recommendations (if they have one), and intimately know their fall model selector list on elegibility for driver selection. In the fall of 1979 NAFA's study reported intent to buy 52 percent compacts and subcompacts. The '79 registration figures for fleet show that 38.5 percent were purchased from these two segments.
Comparing the following year (NAFA's '80 fall survey vs. actual model year registrations) we fire that the fleet managers expected to buy 50 percent compacts (actually they bought 24.9 percent) and 35 percent intermediates (really bought 25.1 percent).
Similarly in the fall of '81 NAFA respondents predicted that they would buy 68.5 percent compacts and 27 percent mid-size cars. Registrations show that the entire fleet market bought 28.4 percent compacts and 25.8 percent intermediates during the following model year.
It is true that "mid-size" may not mean "intermediate" to all fleet buyers and everyone's reporting may not be exactly on the same basis; and, just maybe, some people may change their mind. But with all the hoopla about continued downsizing, NAFA's study last fall predicting that 70 percent of '83 fleet purchases will be compact, and the knowledge that there is an actual trend towards more luxury, standard, and intermediate fleet buying, I don't think Detroit will be concentrating entirely on compact sales.
DOMESTIC REGISTRATIONS -
FLEET PERCENT OF TOTAL (Model Year)
'79
'80
'81
'82
Luxury
Standard
Intermediate
Compact
Sub-Compact
Sports
19.2
25.4
20.1
19.5
9.2
9.1
16.4
20.7
22.2
24.6
13.9
7.8
15.7
20.0
25.1
24.9
9.9
8.8
16.2
20.9
25.8
28.4
11.7
9.7
GELCO & PH&H MODEL YEAR PURCHASES
(Combined Average)
'79
'80
'81
'82
Luxury
Standard
Intermediate
Compact
Sub-Compact
3.4
9.0
47.3
26.8
5.5
3.0
7.2
45.4
38.3
6.5
2.7
4.5
34.5
44.1
6.3
1.7
5.5
32.0
53.9
6.3
More Operations
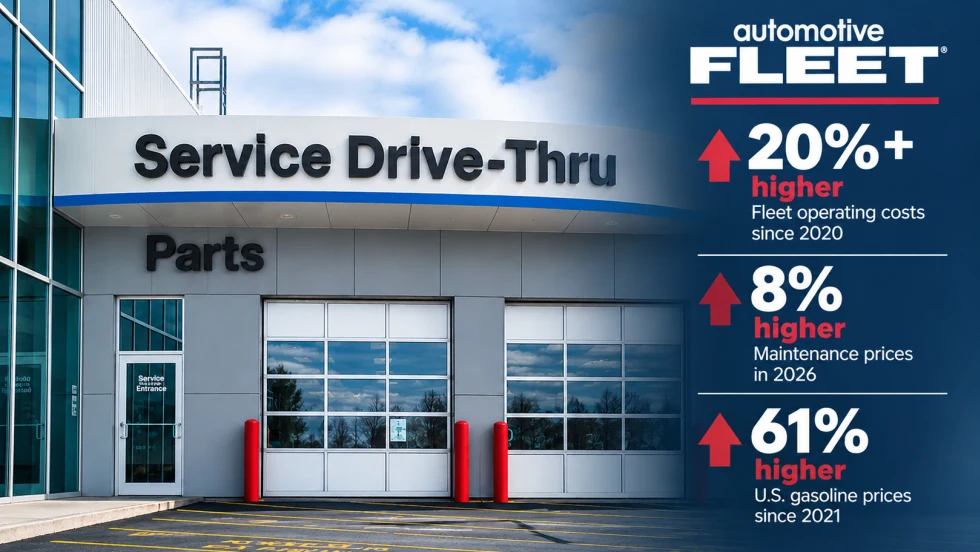
Managing Fleet Costs in an Era of Permanent Volatility
Fleet operating costs have risen more than 20% since 2020, raising a key question: When does extending a vehicle's service life stop making financial sense?
Read More →
The Next Evolution of Fleet Management: Autonomous Operations
This opening keynote session at the Fleet Forward Conference highlights the future of autonomous driving for fleets.
Read More →
How to Reduce the Total Cost of Risk From Catalytic Converter Theft
A stolen catalytic converter can cost fleets far more in downtime and lost productivity than in repairs. A total-cost-of-risk approach can help fleet managers quantify their exposure and prioritize theft prevention.
Read More →
Personal-Use Charges Rise as Vehicle Values Fall | AF News Recap
Personal-use charges are climbing, wholesale used-vehicle values are declining, and commercial fleet sales growth is slowing. This week, we're breaking down the latest fleet data, plus how Element Fleet Management is helping Waymo prepare for its first Canadian robotaxi market.
Read More →
Here's When You Should Make an Exception to Fleet Policy
Fleet policies are designed to create consistency, but not every driver or situation fits neatly within standard rules.
Read More →
AI-Native or AI-Acquired: What Should Fleet Managers Look for in an AI Platform?
Six questions can help fleet managers look beyond AI marketing claims to evaluate integration, data access, and real-world operational performance.
Read More →
A buyer's guide to fleet management software in 2027
Buying fleet management software in 2027 means looking beyond features and price. As fleet operations, technology and expectations evolve, this guide explores what today’s fleet professionals should consider when choosing a system that can deliver value now and adapt to what comes next.
Read More →
What Will Shape the Next Era of Fleet Management?
EVs, AI, and autonomous vehicles are reshaping fleet management. Discover what’s ahead—and how fleet leaders can prepare for the next era.
Read More →
How Fleets Can Recruit and Train Veterans for Technician Roles
Here's how the technician shortage has affected uptime for fleets, and what to do about it.
Read More →
Avis Budget Group Deploys Neology Toll Management Technology Across Major Brands
Neology’s neoFleet platform will manage toll transactions and toll-authority operations for vehicles across Avis, Budget, Payless, Budget Truck and Zipcar.
Read More →