Analyzing Depreciation Trends: 2007 vs. 2006
Depreciation continues to be the largest fleet expense; however, fuel, as a percent of total fleet cost is growing (rapidly). Fuel expense is influencing vehicle acquisition strategies, with a direct bearing on future depreciation.

A multitude of factors influenced fleet vehicle depreciation in 2007 – total mileage, vehicle condition, strength of the resale market, incentive monies, accelerated replacement cycling, and one that is growing in importance, the cost of fuel. How does 2007 depreciation compare with 2006?
We posed this question to survey partners Automotive Resources International (ARI), GE Capital Solutions Fleet Services, LeasePlan USA, PHH Arval, and Wheels Inc. Based on a survey of actual fixed costs incurred by 436,865 commercial fleet vehicles managed by these five fleet management companies, here’s what they told us.
Fuel: Although an operating expense, the high cost of fuel is beginning to influence new-vehicle acquisition decisions, in particular the type and size of vehicles acquired. According to GE, fleets in the next year and beyond will likely change how they view their total fleet expenses from “depreciation is my highest expense” to “fuel is my highest expense.”
“This will create a need for replacement models and plans that put more weight on vehicle expense factors other than just depreciation,” said Eric Hjerpe, digitalization leader for GE Capital Solutions Fleet Services.
Others share the assessment that the high cost of fuel is directly impacting vehicle depreciation.
“Vehicles viewed as more fuel-efficient have outperformed the resale market in recent years. Those that are less fuel-efficient have generally underperformed,” said Greg Corrigan, VP of business intelligence for PHH Arval.
Another factor that promises to play a greater role in depreciation is the growing proliferation of green fleet initiatives. As more companies implement green initiatives to reduce CO2 pollution, it is anticipated there will be changes in how fleets operate and the length of time vehicles are kept in service.
“A reduction in the amount of monthly miles driven may result through better route planning and a continued effort to conserve fuel. The average cap cost may start to decline as fleets start to consider smaller, more fuel-efficient vehicles. Improved manufacturers’ warranties and advanced vehicle technology can also allow longer lifecycles. As a result, the average months-in-service will increase, ultimately improving depreciation,” said Anthony Foursha, manager, strategic services for ARI.
Replacement Cycling: Accelerated replacement ordering influenced fleet depreciation in 2007.
“Many fleets were looking to use depreciation as a financial play in 2007. Depreciation was impacted by accelerated ordering plans that allowed increased incentives from the manufacturers to offset any resale loss,” said Hjerpe. “While not one segment will see a major change in replacement patterns, it will more often be the types of vehicles that replace those units that will have the most impact. Older, less-efficient vehicles will likely be replaced with newer, more efficient or flexible-fuel vehicles,” he added.
Resale Market: Strength in the wholesale used-vehicle market varied by vehicle segment in 2007. “Sedans continue to show strength in the used-vehicle marketplace. Minivans and SUVs are not as strong as sedans and will probably remain that way for the foreseeable future,” said John Bauer, manager of fleet analytics for Wheels. “With the elimination of the Chevrolet Astro and a general need to save fuel, car-based minivans are being used by a number of service fleets. These minivans are usually returned with higher mileage and in worse condition than the same type of vehicles a few years ago,” said Bauer. “In addition, some fleets that previously offered minivans to sales reps have eliminated them and replaced them with sedans.”
In 2007, the inventory of out-of-service fleet vehicles awaiting resale in the wholesale market was in balance with buyer demand. This was the greatest factor contributing to the improvement in resale prices. “Supply and demand factors in the market, in general, have led to a favorable overall resale environment in CY07,” said Corrigan.
During 2007, LeasePlan also reported it experienced a decrease in the monthly depreciation cost for all vehicle segments, compared to CY06. “This decrease is in line with LeasePlan’s expectations due to the fact that the used-vehicle market improved from CY06 levels because of favorable industry and economic conditions. This year-over-year improvement in used-vehicle proceeds realized at auction has resulted in reduced depreciation expense for CY07 terminations,” said Paul Fortin, director, residual value risk management for LeasePlan USA.
Vehicle segments that account for the majority of LeasePlan’s portfolio (intermediate cars, minivans, and SUVs) all experienced decreases in the 3- to 6-percent range, said Fortin.
“Trucks had the lowest depreciation cost per month because fleets keep them in service longer than other vehicle types,” added Bauer.
In recent years, the average service life of fleet vehicles has remained stable.
“We have seen very small increases in service life in the last several years. Since 2004, average months-in-service for sedans has increased by about four months,” said Bauer. “This reflects fleets that have changed their replacement policies and are keeping vehicles in service longer.”
According to Bauer, minivans have shown smaller months-in-service increases than sedans and trucks. The average service life for SUVs was virtually unchanged when comparing 2007 with 2006.
One fleet segment that experienced an increase in months-in-service was compact cars.
“While the compact car average months-in-service increased for 2007, there was a significant decrease for months-in-service in the other vehicle segments,” said Foursha of ARI.
According to ARI, the average months-in-service decreased 15 percent overall from 2006, with minivans and SUVs showing the largest decline. “We estimate this decrease as a result of the increase in average monthly miles. The projection for 2008 shows a slight increase of months-in-service across the board,” said Foursha.
Agreeing is Corrigan of PHH. “Average age has flattened out, as clients have accelerated replacement cycling, looking for more fuel-efficient vehicles.”
Incentives from OEMs were also a key factor in accelerating vehicle replacement cycles.
“Most fleets are staying consistent in the cycling of vehicles unless they have opted for some type of financial pay through replacement, such as pulling cash forward through an accelerated replacement plan,” said Hjerpe. “There also may be a slight trend in replacing larger vehicles with smaller, more efficient options that can serve the same purpose. This pattern is likely to continue into the future,” added Hjerpe.
Fleet capitalized (cap) costs have remained flat over the past several years due to factory incentives.
“Incentives have had the biggest impact on vehicle cost. Although it’s too early to draw conclusions about 2008, some popular models are showing small increases,” said Bauer.
Some cap costs by vehicle segment had a greater decrease in 2007 compared to 2006. “The SUV segment experienced a significant decrease of 8 percent,” said Foursha. “Overall, volume incentives impacted the average cap of the vehicles. Volume incentives appear to have leveled off for 2007.”
According to ARI, the decrease in cap cost for the SUV segment resulted from a combination of both volume incentives and a substitution of compact SUVs in place of fullsize SUVs. “Based on recent trends, it’s estimated that 2008 will remain level when compared to 2007, with a slight decrease in SUVs,” said Foursha.
Another factor contributing to lower cap costs is the trend toward smaller vehicles. “Cap costs are on the decline, primarily attributed to a move toward smaller vehicles,” said Corrigan.
New-model price increases contributed to an increase in capitalized cost; however, in most cases the price increases were offset by fleet incentives monies. “New-vehicle model pricing resulted in a slight increase in cost, but in general, cap costs remained relatively flat in all categories but compact cars,” said Hjerpe.
“Compact cars seem most impacted by the addition of hybrids. Hybrids are quickly becoming a larger segment of more fleets, and we have seen that reflected in ordering statistics. We have also seen a trend for fleets to offer compact or mid-size vehicles with more options to offset any driver dissatisfaction,” Hjerpe added.
Let me know what you think.
More Remarketing
When Should a Fleet Repair Vehicle Damage Before Remarketing?
Not every dent, scratch, or mechanical issue is worth fixing before selling a fleet vehicle. Learn how to weigh repair costs, resale value, market demand, and downtime to determine when reconditioning pays off and when selling as-is makes more sense.
Read More →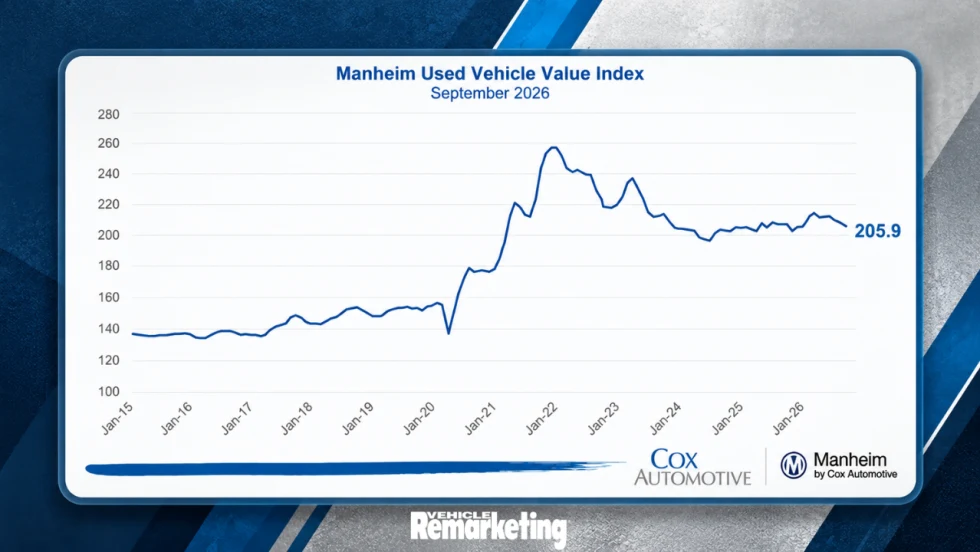
Wholesale Used-Vehicle Values Fall as Cox Automotive Cuts 2026 Forecast
Wholesale used-vehicle prices declined in September as depreciation accelerated, prompting Cox Automotive to lower its year-end forecast.
Read More →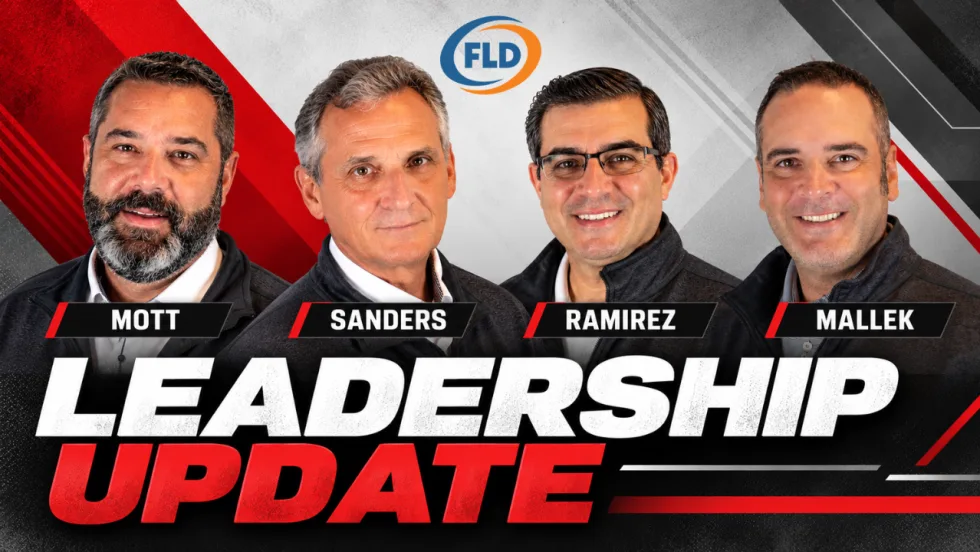
FLD Promotes Three Executives in Leadership Changes
FLD has promoted three longtime executives, naming Gary Mott CEO, Richard Mallek president, and Ron Sanders managing partner.
Read More →
Ford Pro Launches Certified Pre-Owned Program for Commercial Vehicles
Ford Pro Advantage will offer certified pre-owned Class 1-7 commercial vehicles through more than 700 Ford Pro Commercial Vehicle Centers.
Read More →
Copart to Acquire ACV in $1.9 Billion Deal
The acquisition would expand Copart beyond its traditional salvage business into dealer-to-dealer wholesale remarketing while adding ACV’s vehicle data, inspection, and valuation technology.
Read More →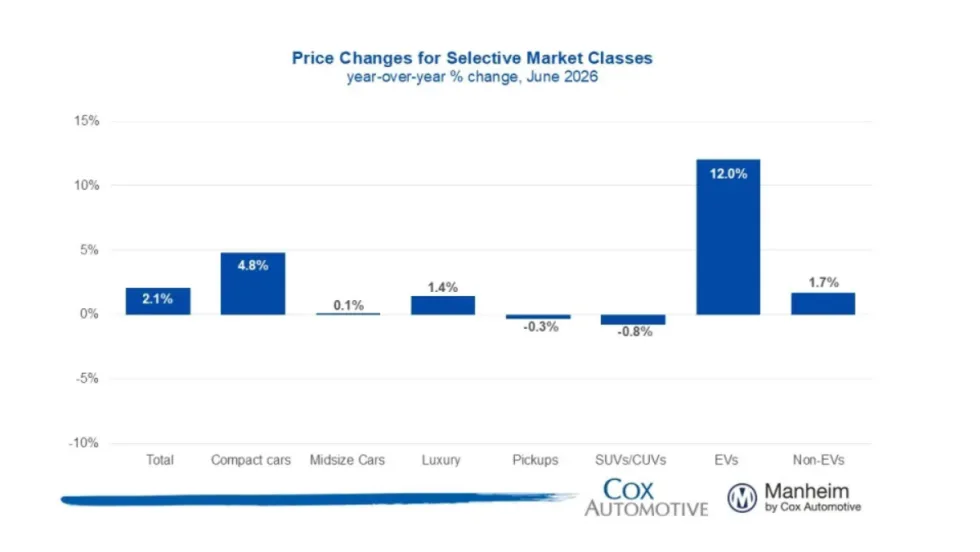
Manheim Index Shows Used-Vehicle Wholesale Prices Up 2.1% in June
The market is seeing stronger appreciation in older used vehicles this year, and the most affordable segments have been among the year’s best performers.
Read More →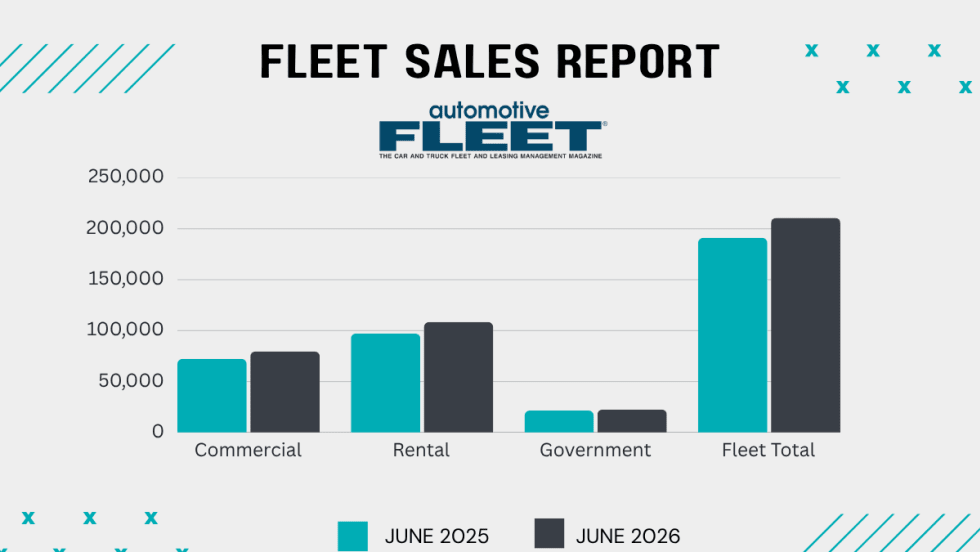
Commercial Fleet Sales Contribute To June, YTD Gains
The fleet sector has boosted its vehicle purchases at a reliable pace in the first half of this year compared with 1H 2025.
Read More →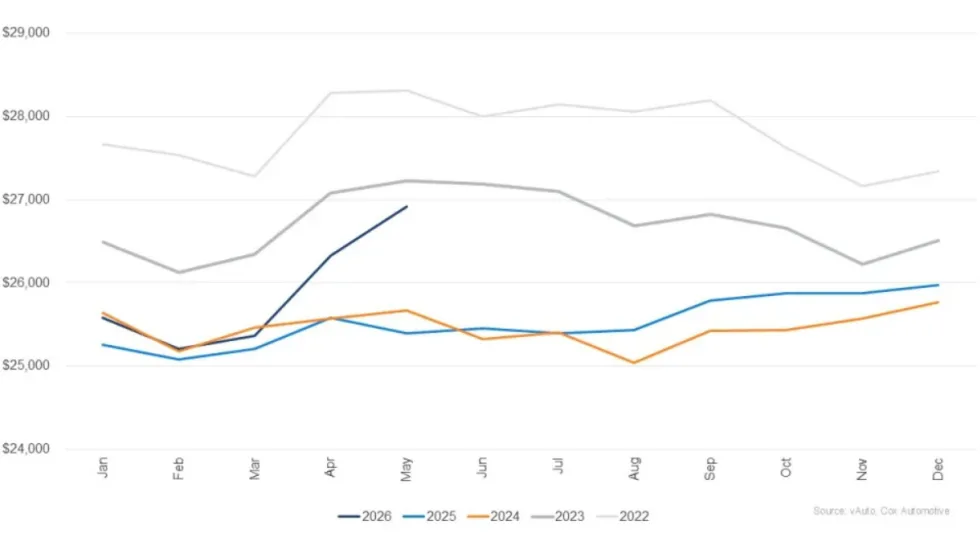
Used Vehicle Prices Climb Higher As Sales Pace Slows
The higher prices at used retail reflect strong wholesale values earlier in the spring, particularly for older, more affordable vehicles.
Read More →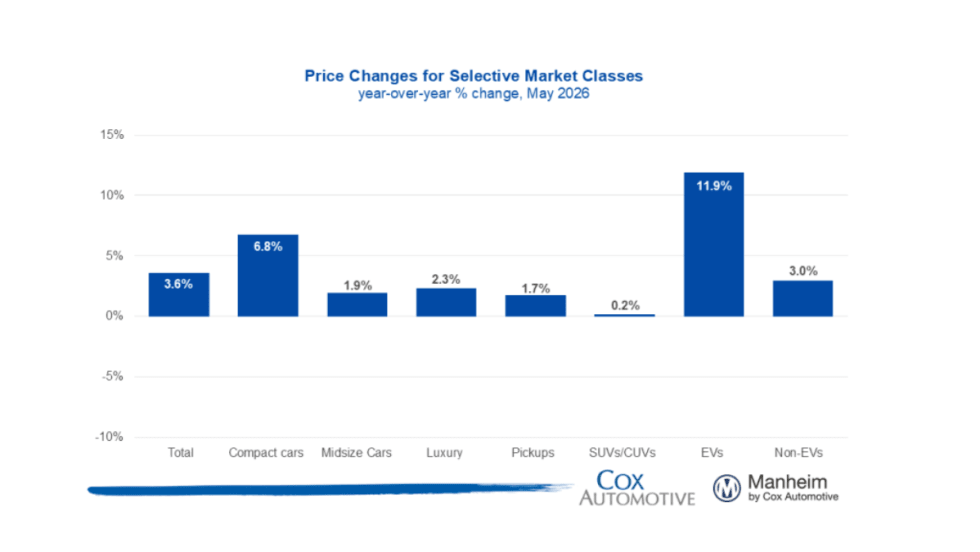
Wholesale Used Vehicle Market Sustains Moderate Rise In Values, Prices
Trends continue to normalize after a strong start to the year, as consumers contend with higher gas prices in the coming summer months.
Read More →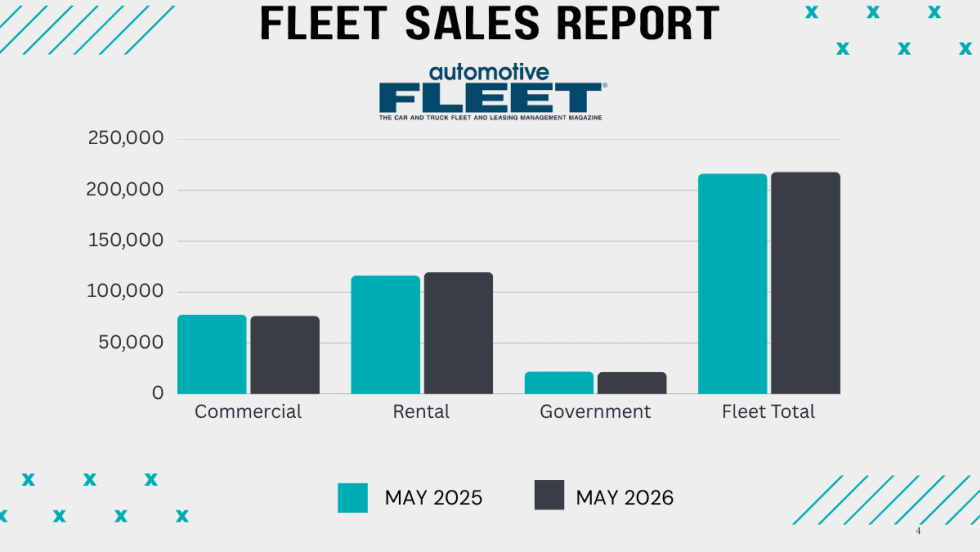
Commercial Fleet Sales Still Lead Sectors Despite May Mini Dip
The U.S. economy's continued growth and positive business investment are creating a favorable environment for fleet vehicle demand.
Read More →