

An Introspective View of Bank Leasing
T.J. Johnson's automotive marketing background began with GM in 1956. He is now leasing executive with the Greyhound Leasing and Financial Corp.
One gets the impression that a lot of Chicago banking people, with their eyes on car leasing, are interested in the success or failure of the First Lease enterprise. Its failure will send many scurrying with their lease agreements to the paper shredders. Success will bring a host of imitators. Yet neither of thee happenings are desirable. With First Lease's success, imitators will clutter the marketplace; with failure, potentially capable institutions will turn their backs on an outstanding banking opportunity.
Leasing, with very few exceptions, has escaped the grasp of the automobile dealer. Independents have flourished and waned. Large rental companies have experimented with success and disappointments. Meanwhile, the common denominator to successful leasing remains: Properly selected vehicles, properly curtailed, driven by properly selected customers. All leasing companies follow this credo, at least in the beginning. But leasing, after all, is a financial labyrinth offering exotic tax benefits and mystical paper maneuvering! Creating an aura of mystery in which failing companies lose sight of the simple debit and credit accounting, and forget what it was they were in business to do in the first place ... to lease cars.
The exposure to a bank financing the outstandings of an outside leasing company is wide and complex. Vulnerability begins with the customer, unless the bank has control over the credit acceptance of the lessee. Then the bank must beware of the internal moods of the lessor. Is he grating easy credit, shaving curtailments and packing the value of returning vehicles to improve a sagging financial statement, or using his leverage to expand to other enterprises? Is he selecting bad merchandise? Or, is he selling the operation to a less desirable operator? Ironically, banks continue to finance outside leasing activities, accepting greater exposure than if they themselves were the lessor. A bank directing the thrust of its own leasing entity knows its motivations.
Automobile leasing, to be successful, requires unwavering procedural controls and close financial supervision. Many car dealers, by nature, lack the necessary disciplines. And some independents have become euphoric in financial maneuverings, giving automobile leasing a less than desirable profile in the financial theater. Car leasing is relatively young in the field of financing opportunities, and, as in most youthful endeavors, some stumbling is to be expected. The regulatory conduct inherent in a financial institution lends itself well to the supervision of a leasing enterprise. Therefore, when a bank takes on a car leasing function, it is not extending its routine unnaturally. It is an accession to what it already does well.
More Operations
Reading the Global Signals: What AI and the Energy Transition Mean for Fleets Now
How can fleet managers navigate a never-ending, changing industry landscape?
Read More →
90% Use Telematics. Are Fleets Getting Safer? | AF News Recap
This week, we're breaking down which industries have the highest rates, how Jamie McKay manages 2,400 vehicles, what's happening with the 2027 fleet awards, and why software-defined vehicles could introduce new costs.
Read More →
What's Best Handled by an FMC, and What's Better Done Directly?
Fleet managers continue to rely on FMCs for essential services but are taking a closer look at where working directly with suppliers can improve efficiency and responsiveness.
Read More →
Fleet Meets: Erin Gilchrist
Meet Erin Gilchrist, the inaugural Mike Antich Spirit of Fleet Award winner, as she shares insights on leadership, mentorship, the power of industry connections, and why people remain at the heart of fleet's future.
Read More →
How 2026 Fleet Visionary Jamie McKay Manages 2,400 Vehicles Across 37 States
How do you keep 2,400 vehicles running across 37 states? Fleet Visionary Award winner Jamie McKay shares how collaboration, flexibility, and a few simple strategies help her tackle fleet management challenges at Aptive Pest Control.
Read More →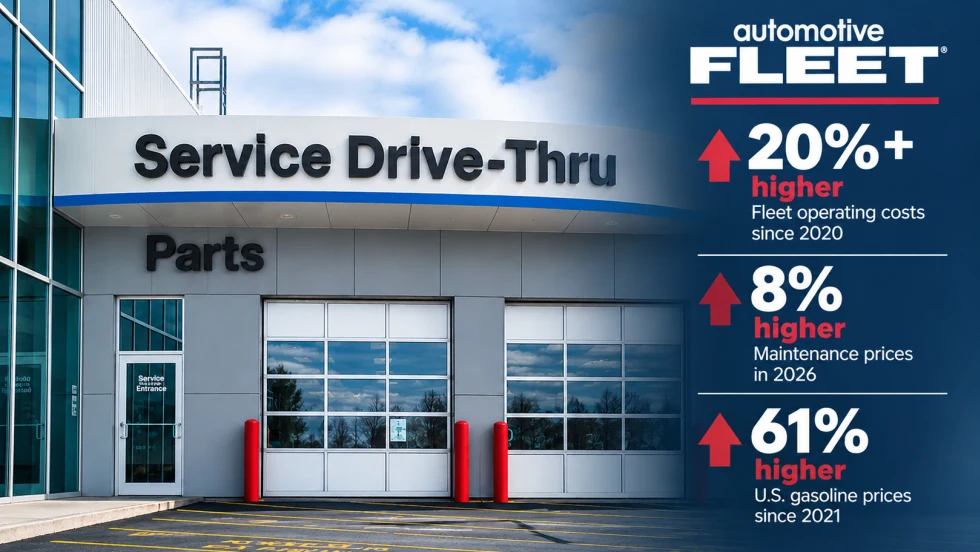
Managing Fleet Costs in an Era of Permanent Volatility
Fleet operating costs have risen more than 20% since 2020, raising a key question: When does extending a vehicle's service life stop making financial sense?
Read More →
The Next Evolution of Fleet Management: Autonomous Operations
This opening keynote session at the Fleet Forward Conference highlights the future of autonomous driving for fleets.
Read More →
How to Reduce the Total Cost of Risk From Catalytic Converter Theft
A stolen catalytic converter can cost fleets far more in downtime and lost productivity than in repairs. A total-cost-of-risk approach can help fleet managers quantify their exposure and prioritize theft prevention.
Read More →
Personal-Use Charges Rise as Vehicle Values Fall | AF News Recap
Personal-use charges are climbing, wholesale used-vehicle values are declining, and commercial fleet sales growth is slowing. This week, we're breaking down the latest fleet data, plus how Element Fleet Management is helping Waymo prepare for its first Canadian robotaxi market.
Read More →
Here's When You Should Make an Exception to Fleet Policy
Fleet policies are designed to create consistency, but not every driver or situation fits neatly within standard rules.
Read More →