A Matter of Interest - Understanding Where Interest Savings Add Up
Watching the pennies on the interest basis of the lease can add up to significant savings.
William G. "Bill" Schneider, fleet administrator for Employers Insurance of Wausau, stalwart of the Chicago Regional National Association of Fleet Administrators, and regular contributor to Automotive Fleet, considers this one of the most significant and ambitious pieces he has ever written in his field.
Of the many clauses in a leasing contract, the one least understood is the one spelling out monthly rental payments. True, the amount of money involved is specifically stated, but the calculation can leave many questions unanswered.
Monthly rental usually comprises the depreciation which is based upon a specific percentage factor of the capitalized value of the car, interest, handling of service fee, and any state or local tax applicable at point of delivery or area where the car is to be kept. The negotiable items between lessor and lessee will be the interest and service or handling fee. The pattern is usually based upon fleet size, location of cars plus the expertise and experience of each party and their ability to bargain.
This then leaves interest. Often an "error of assumption" is made by one or both parties that there is only one way to calculate interest. This is not true. Let's examine the question of interest and attempt to shed light upon the many facets of its calculation. The basis for basic annuity formulations can be found in both high school and college textbooks and numerous professional publications as well.
The basis of interest must be specifically pinpointed, for example: one or two points over prime rate with the rate source having a reference point such as a specific bank or Federal Reserve district. It is possible, when a method of computing interest is agreed upon, for a complete schedule of payments showing the applicable factors for each monthly payment on a car to be included as part of the contract. This will facilitate checking the calculation for any car by either party at the time a unit is put into service. Upon notice from a leasing company of a prime rate change, the new factors can be used to verify any rental charges after the rate change.
The subject of interest computation is an intriguing one, especially when one can take a given rate and come up with four mathematically correct answers-all different. The operational cost of a fleet with good cost control records can and should be measured in mills, pennies, nickels, and dimes. Interest is a good place to begin. Assume that a fleet has adopted the standard size middle-line car with a cost of $3,000. Again assume that the cars will be in service 30 months and a two percent per month depreciation factor will be used. Assume still further that a nine percent interest rate is used upon a specific bank Federal Reserve District. Finally, assume that a sound actuarial basis will be used to derive the possible and applicable formulation of the interest factors. For this basis, let's use the annuity formula with which all of the larger banks are familiar. We then arrive at the four following methods:
MethodI-Payment at the end of the month using a nominal rate.
MethodII-Payment at the beginning of the month using a nominal rate.
MethodIII-Payment at the end of the month using an effective rate.
MethodIV-Payment at the beginning of the month using an effective rate.
Utilizing the assumption indicated above and applying the four methods indicated here, the following interest factors are developed:
Months | Method I | Method II | Method III | Method IV |
1-2 | .00668 | .006490 | .006427 | .006238 |
13-24 | .004888 | .004703 | .004697 | .004520 |
25-30 | .003088 | .002916 | .002967 | .002803 |
It becomes readily apparent, by comparison of the figures resulting from solving the annuity formula that a difference emerges in the fourth digit. While this is not a truly significant factor at this point, let's go one step further.
Applying these interest factors of the car price of $3,000 and then multiplying the result by 12 months, a dollar and cents difference appears:
Months | Method I | Method II |
1-12 | 20.06 x 12 = 240.72 | 19.47 x 12 = 233.64 |
13-24 | 14.66 x 12 = 175.72 | 14.11 x 12 = 169.32 |
25-30 | 9.26 x 6 = 55.56 | 8.75 x 6 = 52.50 |
Total | 472.20 | 455.46 |
Months | Method III | Method IV |
1-12 | 19.28 x 12 = 231.36 | 18.71 x 12 = 224.52 |
13-24 | 14.09 x 12 = 169.08 | 13.56 x 12 = 162.72 |
25-30 | 8.90 x 6 = 53.40 | 8.41 x 6 = 50.46 |
Total | 453.84 | 437.70 |
Again, this seems trivial since the spread from the highest to the lowest, or from Method I to Method IV is only $34.50 over a period of 30 months or only $1.15 per month. But, only?
Let's now take a look at what takes place when this difference is multiplied by 100, 500, 1,000, 1,500 or 2,000 cars.
Number of Cars | Method I | Method II | Method III | Method IV |
100 | 47,220 | 45,006 | 45,384 | 43,770 |
500 | 236,100 | 225,030 | 226,920 | 226,920 |
1,000 | 472,200 | 450,060 | 453,840 | 437,700 |
1,500 | 708,300 | 675,090 | 680,760 | 656,550 |
2,000 | 944,400 | 900,120 | 907,680 | 875,400 |
With 100 cars, the difference between Method 1 and Method IV, the extreme of this chart, is $3,450 over a period of 30 months. The difference now becomes significant. But wait! What's the difference between these two methods when 1,000 cars are involved? Simple arithmetic tells us it is $34,500 for 30 months or $1,150 each month. In the event you have a 2,000 car fleet operation, the difference jumps to $69,000;--$2,300 per month!
The amounts indicated here that theoretically can be saved are the extremes between Method I and Method IV. Between the optimum savings illustrated here, there is a variation with the least expensive interest method being method number IV.
The purpose of this exercise is not to teach financial wizardry in one easy lesson, but only to create awareness of an area in which substantial savings-or waste-can be produced. Indeed, it should be stressed that the fleet administrator doesn't need a degree in accounting to negotiate superior interest arrangements under a leasing contract. If he has the facts and the factors, he needs nothing else but a pencil and plenty of scratch paper.
*The nominal rate represents the rate used in computations where such rate reflects the number of conversion periods.
**The effective rate is the annual rate equivalent to a given nominal rate. It is the rate actually earned per year.
More Operations
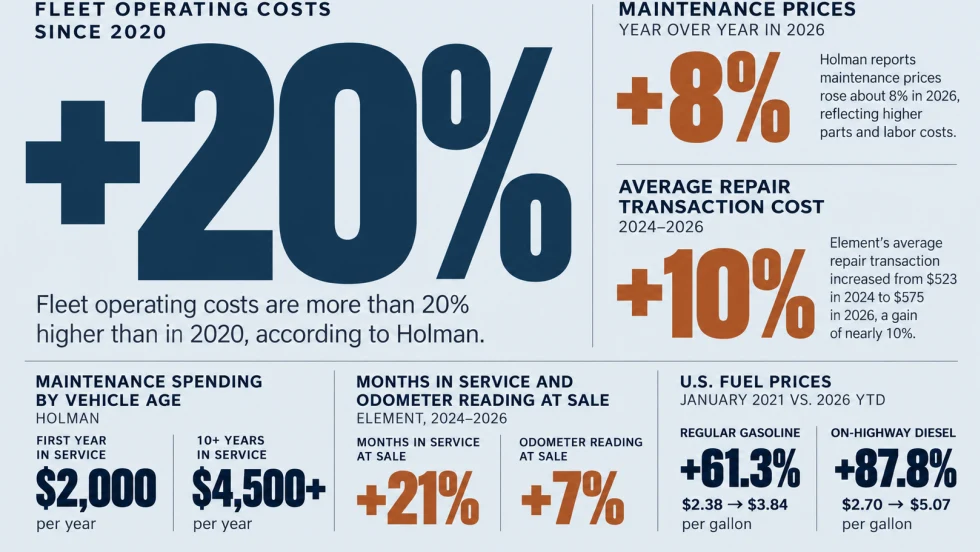
Managing Fleet Costs in an Era of Permanent Volatility
Fleet operating costs have risen more than 20% since 2020, raising a key question: When does extending a vehicle's service life stop making financial sense?
Read More →
The Next Evolution of Fleet Management: Autonomous Operations
This opening keynote session at the Fleet Forward Conference highlights the future of autonomous driving for fleets.
Read More →
How to Reduce the Total Cost of Risk From Catalytic Converter Theft
A stolen catalytic converter can cost fleets far more in downtime and lost productivity than in repairs. A total-cost-of-risk approach can help fleet managers quantify their exposure and prioritize theft prevention.
Read More →
Personal-Use Charges Rise as Vehicle Values Fall | AF News Recap
Personal-use charges are climbing, wholesale used-vehicle values are declining, and commercial fleet sales growth is slowing. This week, we're breaking down the latest fleet data, plus how Element Fleet Management is helping Waymo prepare for its first Canadian robotaxi market.
Read More →
Here's When You Should Make an Exception to Fleet Policy
Fleet policies are designed to create consistency, but not every driver or situation fits neatly within standard rules.
Read More →
AI-Native or AI-Acquired: What Should Fleet Managers Look for in an AI Platform?
Six questions can help fleet managers look beyond AI marketing claims to evaluate integration, data access, and real-world operational performance.
Read More →
A buyer's guide to fleet management software in 2027
Buying fleet management software in 2027 means looking beyond features and price. As fleet operations, technology and expectations evolve, this guide explores what today’s fleet professionals should consider when choosing a system that can deliver value now and adapt to what comes next.
Read More →
What Will Shape the Next Era of Fleet Management?
EVs, AI, and autonomous vehicles are reshaping fleet management. Discover what’s ahead—and how fleet leaders can prepare for the next era.
Read More →
How Fleets Can Recruit and Train Veterans for Technician Roles
Here's how the technician shortage has affected uptime for fleets, and what to do about it.
Read More →
Avis Budget Group Deploys Neology Toll Management Technology Across Major Brands
Neology’s neoFleet platform will manage toll transactions and toll-authority operations for vehicles across Avis, Budget, Payless, Budget Truck and Zipcar.
Read More →